Post-Election Breather: Contracts Cool While the Shelf Keeps Thinning
After the strongest week of the fall, Manhattan buyers took a step back. The borough signed 189 contracts, down 23% from last week’s highest level since June, and Brooklyn signed 115, a second straight weekly dip. The supply side kept tightening, though: Manhattan inventory fell for a third consecutive week to 5,897 homes, the lowest since late September, and new listings declined for an eighth straight week. Pending sales rose in both boroughs for a second week as earlier contracts continued to post.
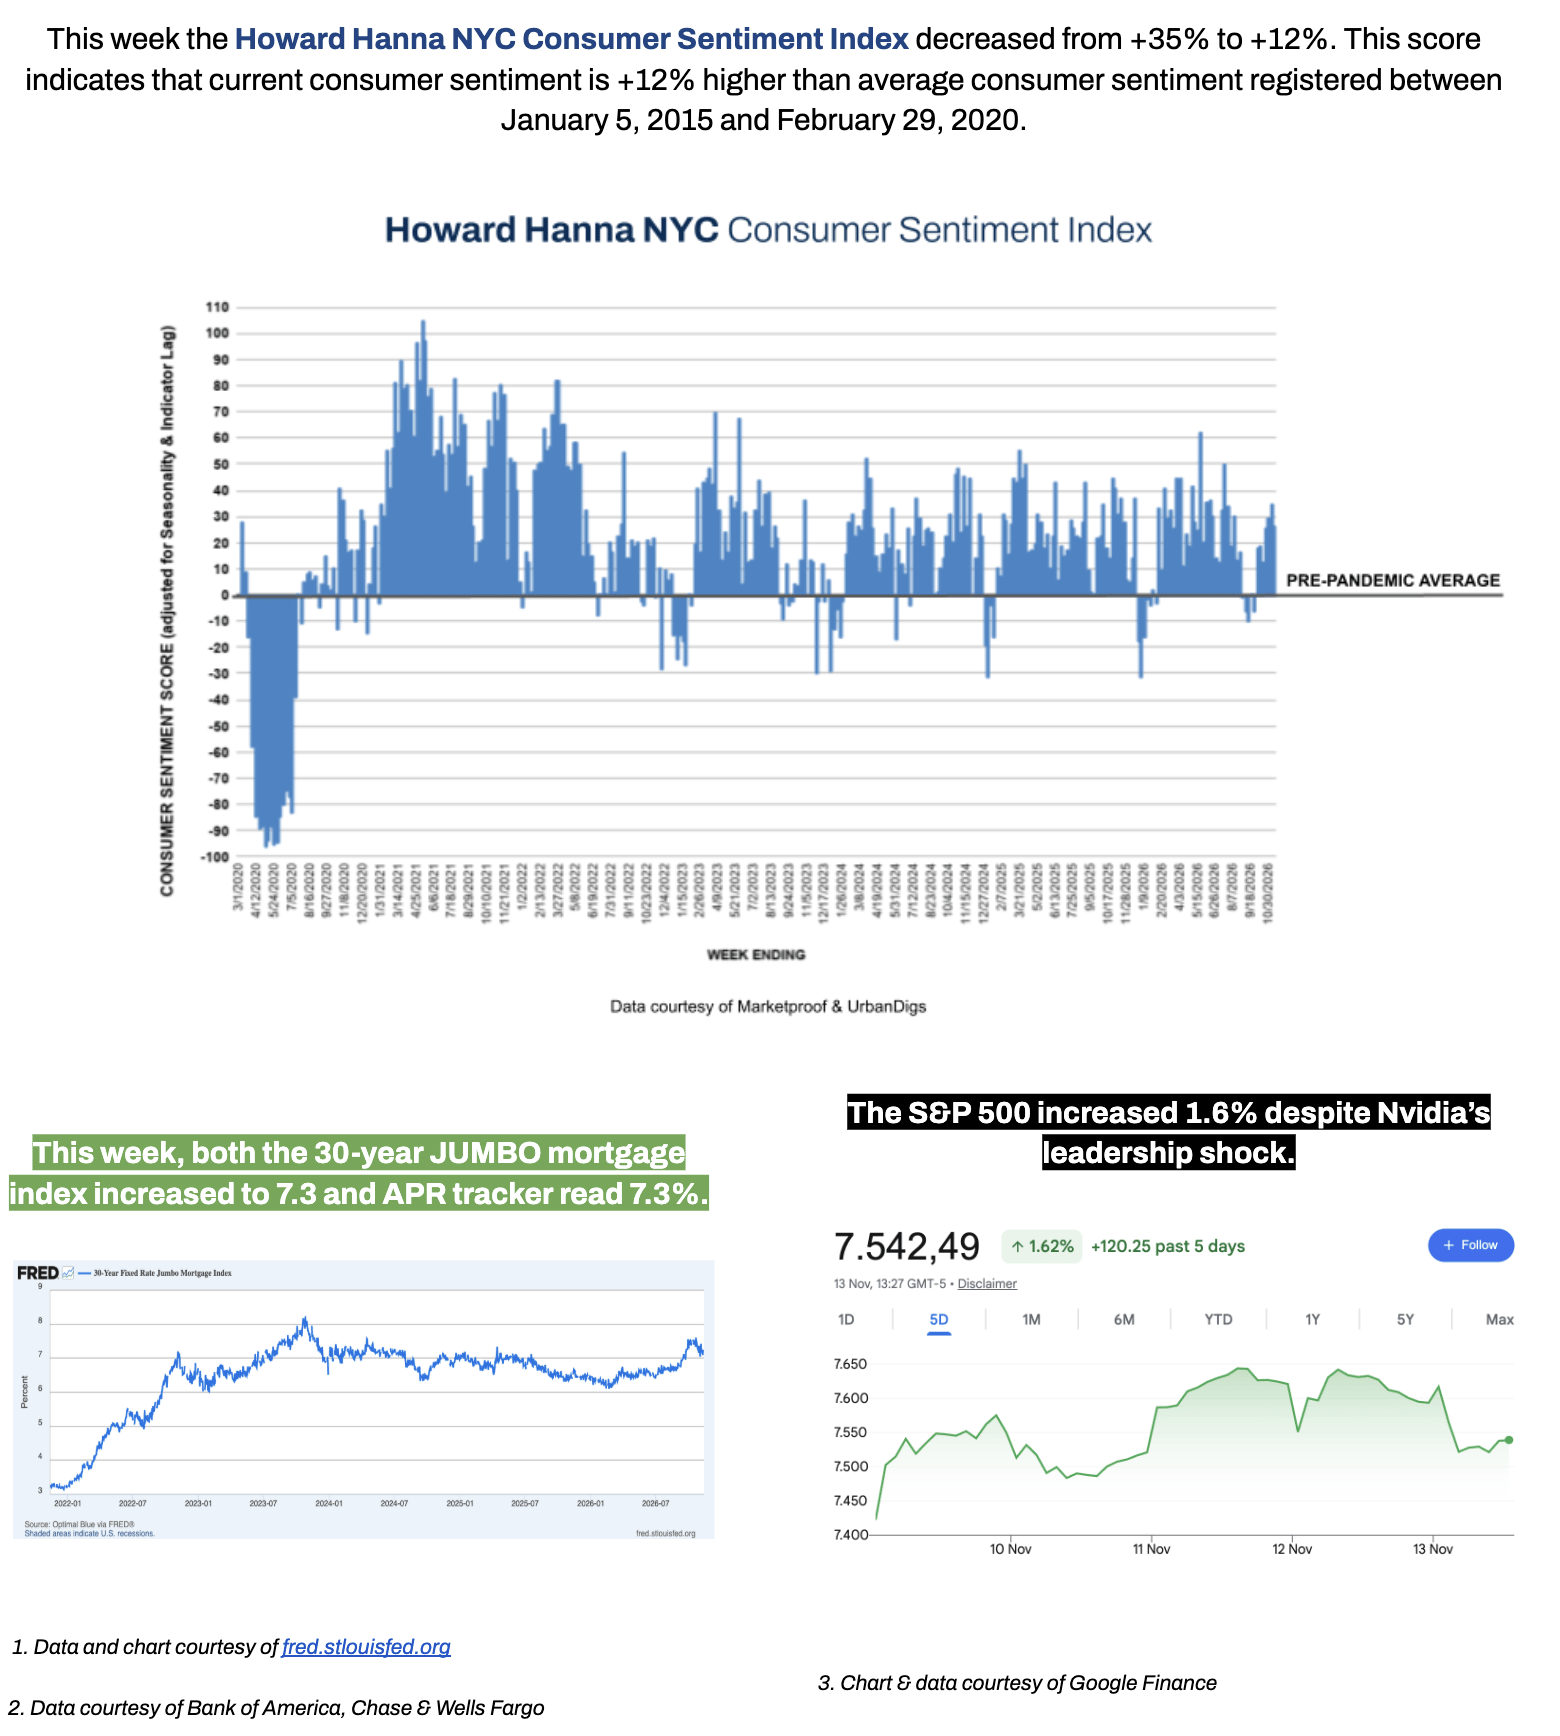
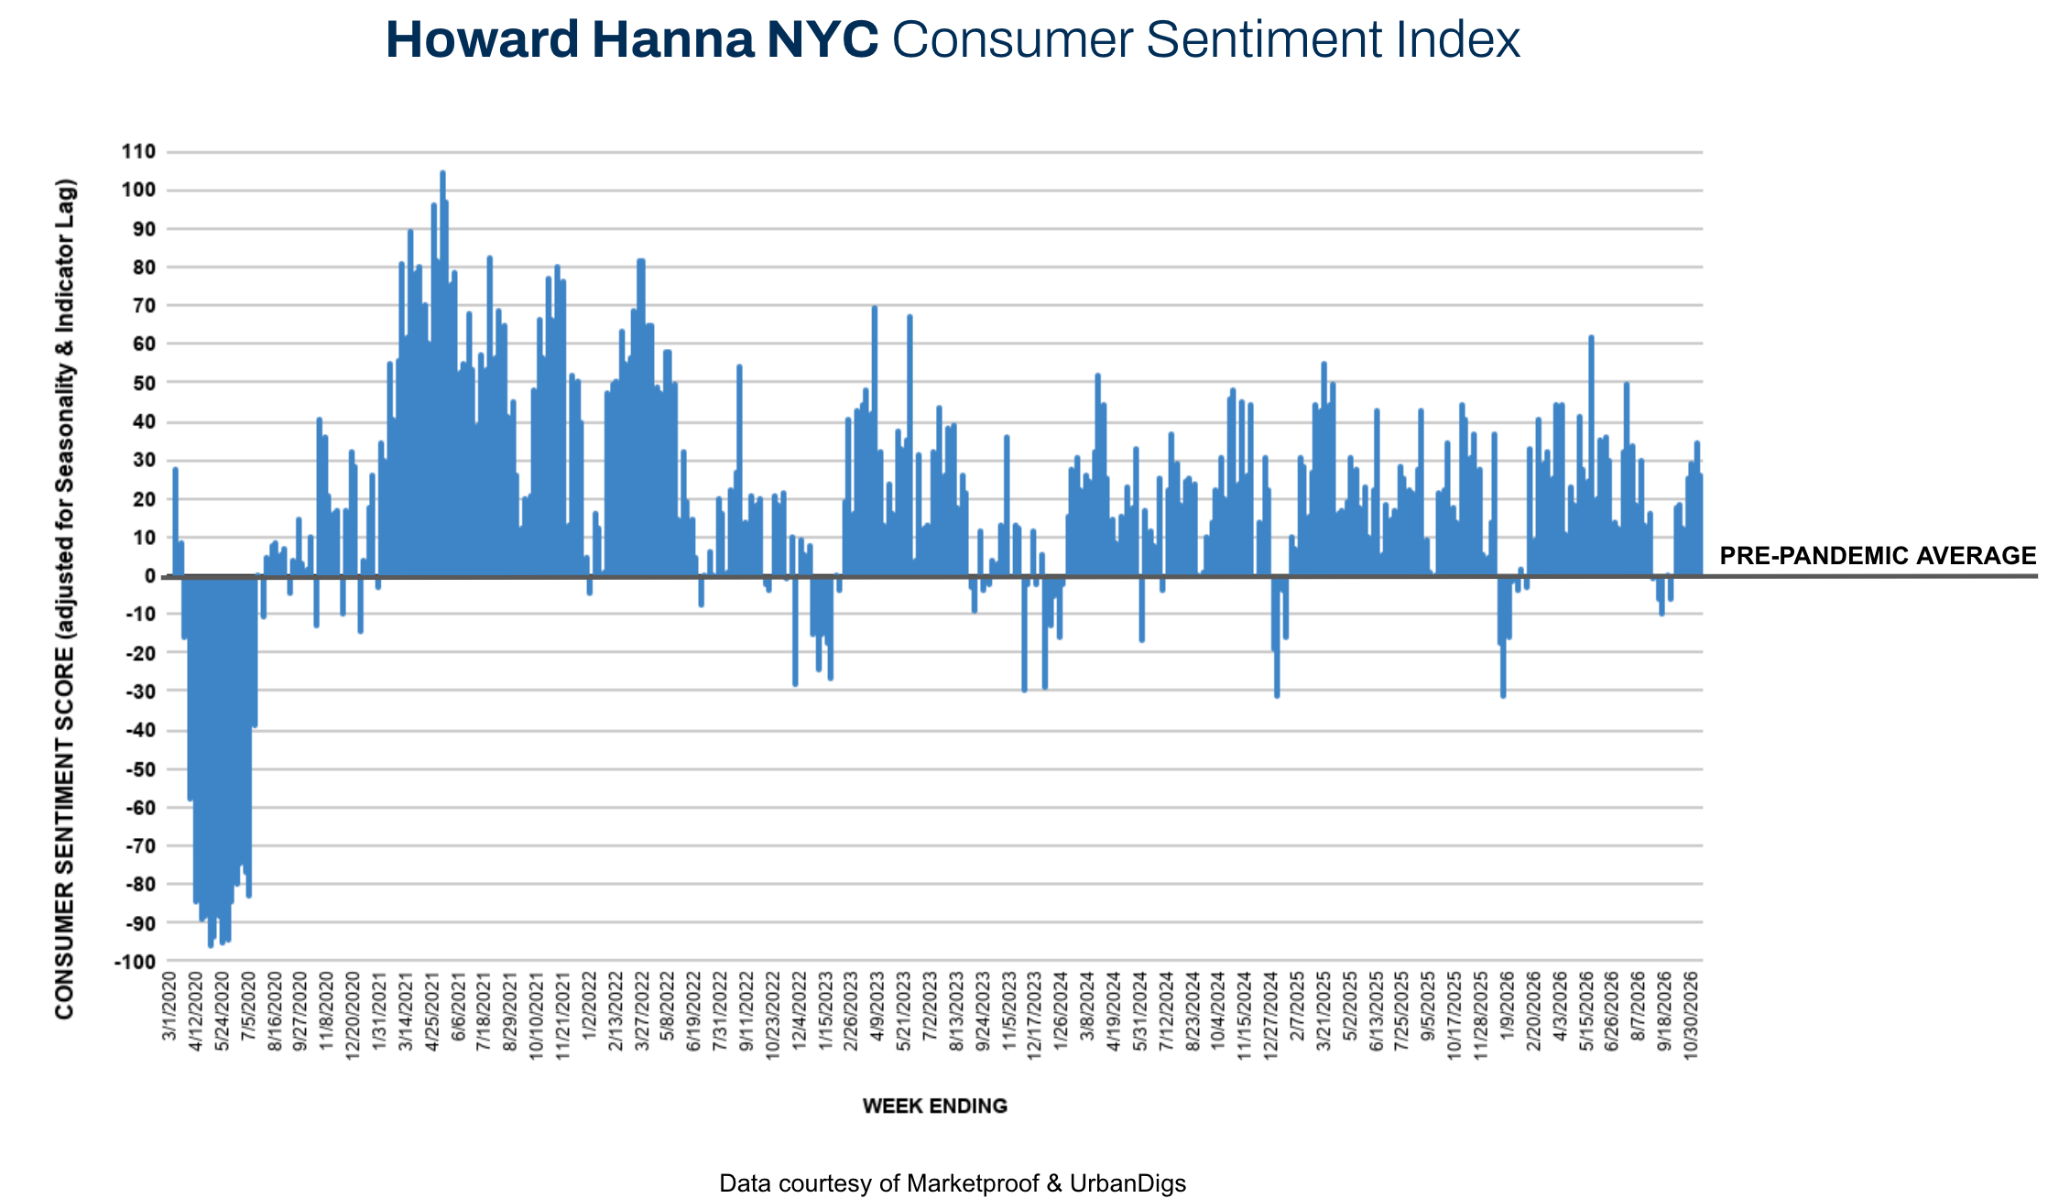
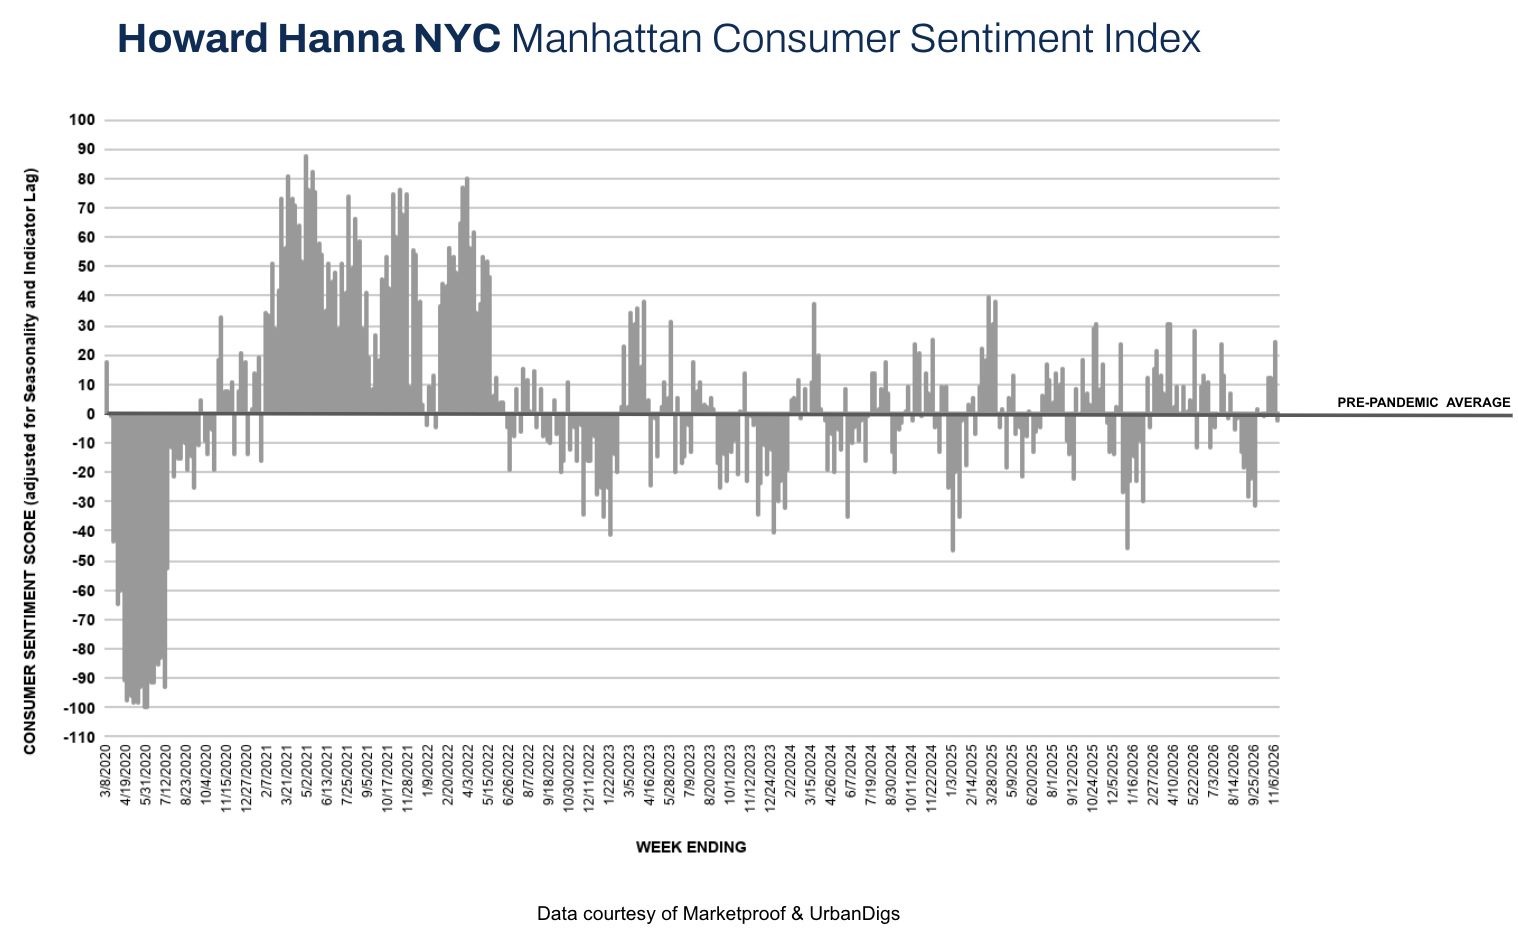
The Howard Hanna NYC Consumer Sentiment Index decreased from +35% to +12%, a sharp pullback from its fall high that still leaves it above its pre-pandemic average. One softer contract week after a surge is not a trend, but it is a reminder that the late-fall window is narrowing.
What This Means for the Last Month of Fall 2026
For buyers: This week offered a little breathing room. With contract activity cooling, sellers who have been on the market since September may be more open to negotiation. But the shelf is still shrinking: Manhattan new listings are 12% below last year and have fallen eight weeks in a row, so the choice available now is likely the widest you will see until spring.
For sellers: Competition from new listings is the lightest since early September, which works in your favor. At the same time, a softer contract week is a signal to stay disciplined on price. With Thanksgiving less than two weeks away, homes that are priced right now have the best chance of going into contract before the holiday slowdown.
Overall, the market is easing into its seasonal year-end pattern: fewer new listings, a gradually thinning shelf, and contract activity that moves week to week around a still-healthy pace. Pending pipelines are building in both boroughs, which points to solid closing volume into December. The next two weeks will show whether last week’s surge or this week’s pullback is the better guide to how the year finishes.
This Past Week: Please see the updated metrics below:
Manhattan Supply: A Third Straight Decline as New Listings Fall for an Eighth Week
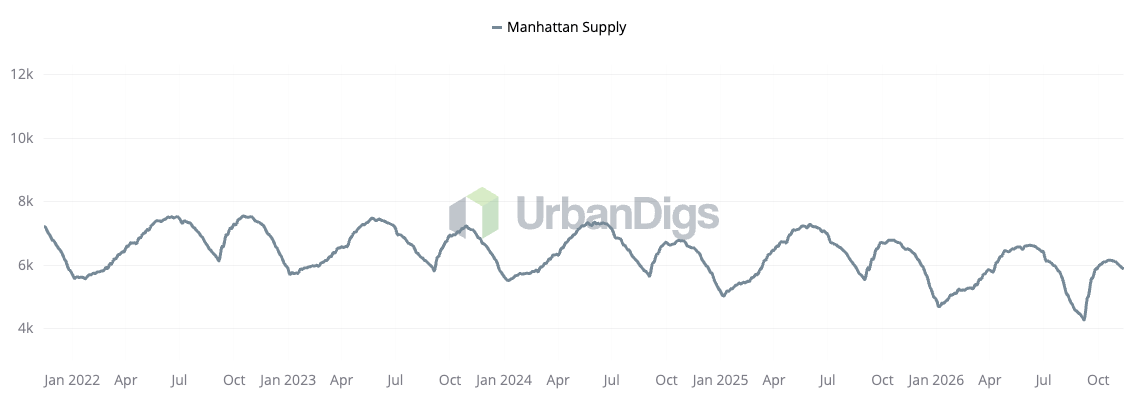
Manhattan active inventory fell to 5,897 homes (−1.6% week-over-week | −9.7% year-over-year), a third consecutive weekly decline and the lowest count since late September. New listings totaled 221 units (−6% week-over-week | −12% year-over-year), an eighth straight weekly decline and the lowest since the start of September.
New listings are now down more than 60% from their mid-September peak of 560, and inventory has fallen by about 260 homes in three weeks. The seasonal drawdown is well underway, and with the holidays ahead, Manhattan’s shelf is likely to keep thinning through December.
Data courtesy of UrbanDigs
Brooklyn Supply: Holding Steady Above Last Year
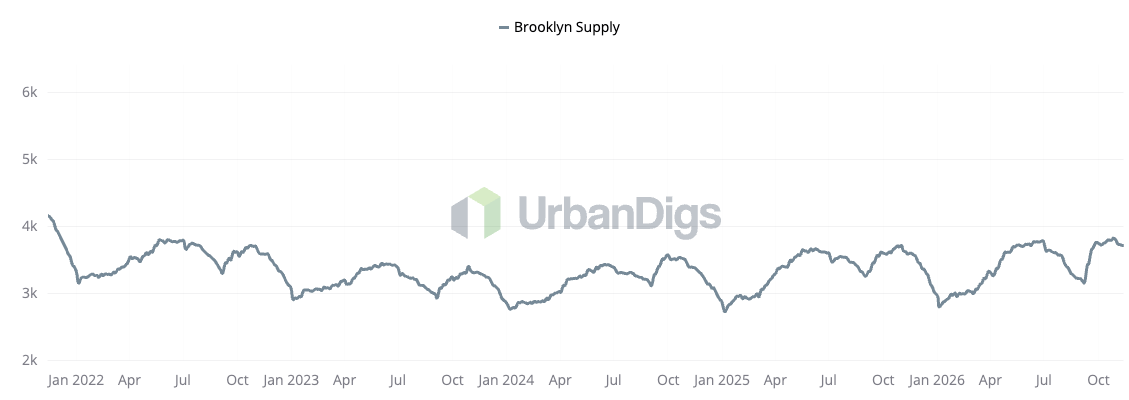
Brooklyn inventory fell to 3,725 homes (−0.1% week-over-week | +3.4% year-over-year), edging lower for a second straight week. New listings totaled 171 units (+0.6% week-over-week | −8% year-over-year), unchanged from last week and now below last year’s pace.
Brooklyn’s inventory has leveled off about 2% below its late-October high for the year and remains above last year, so buyers there still have more choice than a year ago. With new listings flat, the borough’s seasonal decline is likely to be gradual.
Data courtesy of UrbanDigs
Pending Sales: Both Pipelines Build for a Second Week
Pending sales rose again in both boroughs, as the strong late-October and early-November contract weeks continued to work their way into the pipeline. That sets up a healthy run of closings into year-end.
- Manhattan pending sales: up +0.9% week-over-week to 2,995 units, the highest level since mid-September.
- Brooklyn pending sales: up +0.5% week-over-week to 1,858 units, a second consecutive weekly gain.
Manhattan Consumer Sentiment: A Pause After the Surge
Manhattan recorded 189 signed contracts (−23% week-over-week | −12% year-over-year), the fewest since early October, following last week’s highest count since June.
The Howard Hanna NYC Manhattan Consumer Sentiment Index decreased from +25% to −2%, slipping just below its pre-pandemic average. A week of slower contracts against a shelf that is still relatively full pulls this gauge down quickly; with inventory now falling, a rebound in contract activity would bring it back into positive territory.
Brooklyn Consumer Sentiment: Easing, Still Well Above Average
Brooklyn recorded 115 signed contracts (−6% week-over-week | −20% year-over-year), a second weekly decline, measured against a strong mid-November last year.
The Howard Hanna NYC Brooklyn Consumer Sentiment Index decreased from +58% to +49%, a second straight pullback that still leaves the borough well above its pre-pandemic average and comfortably ahead of Manhattan.
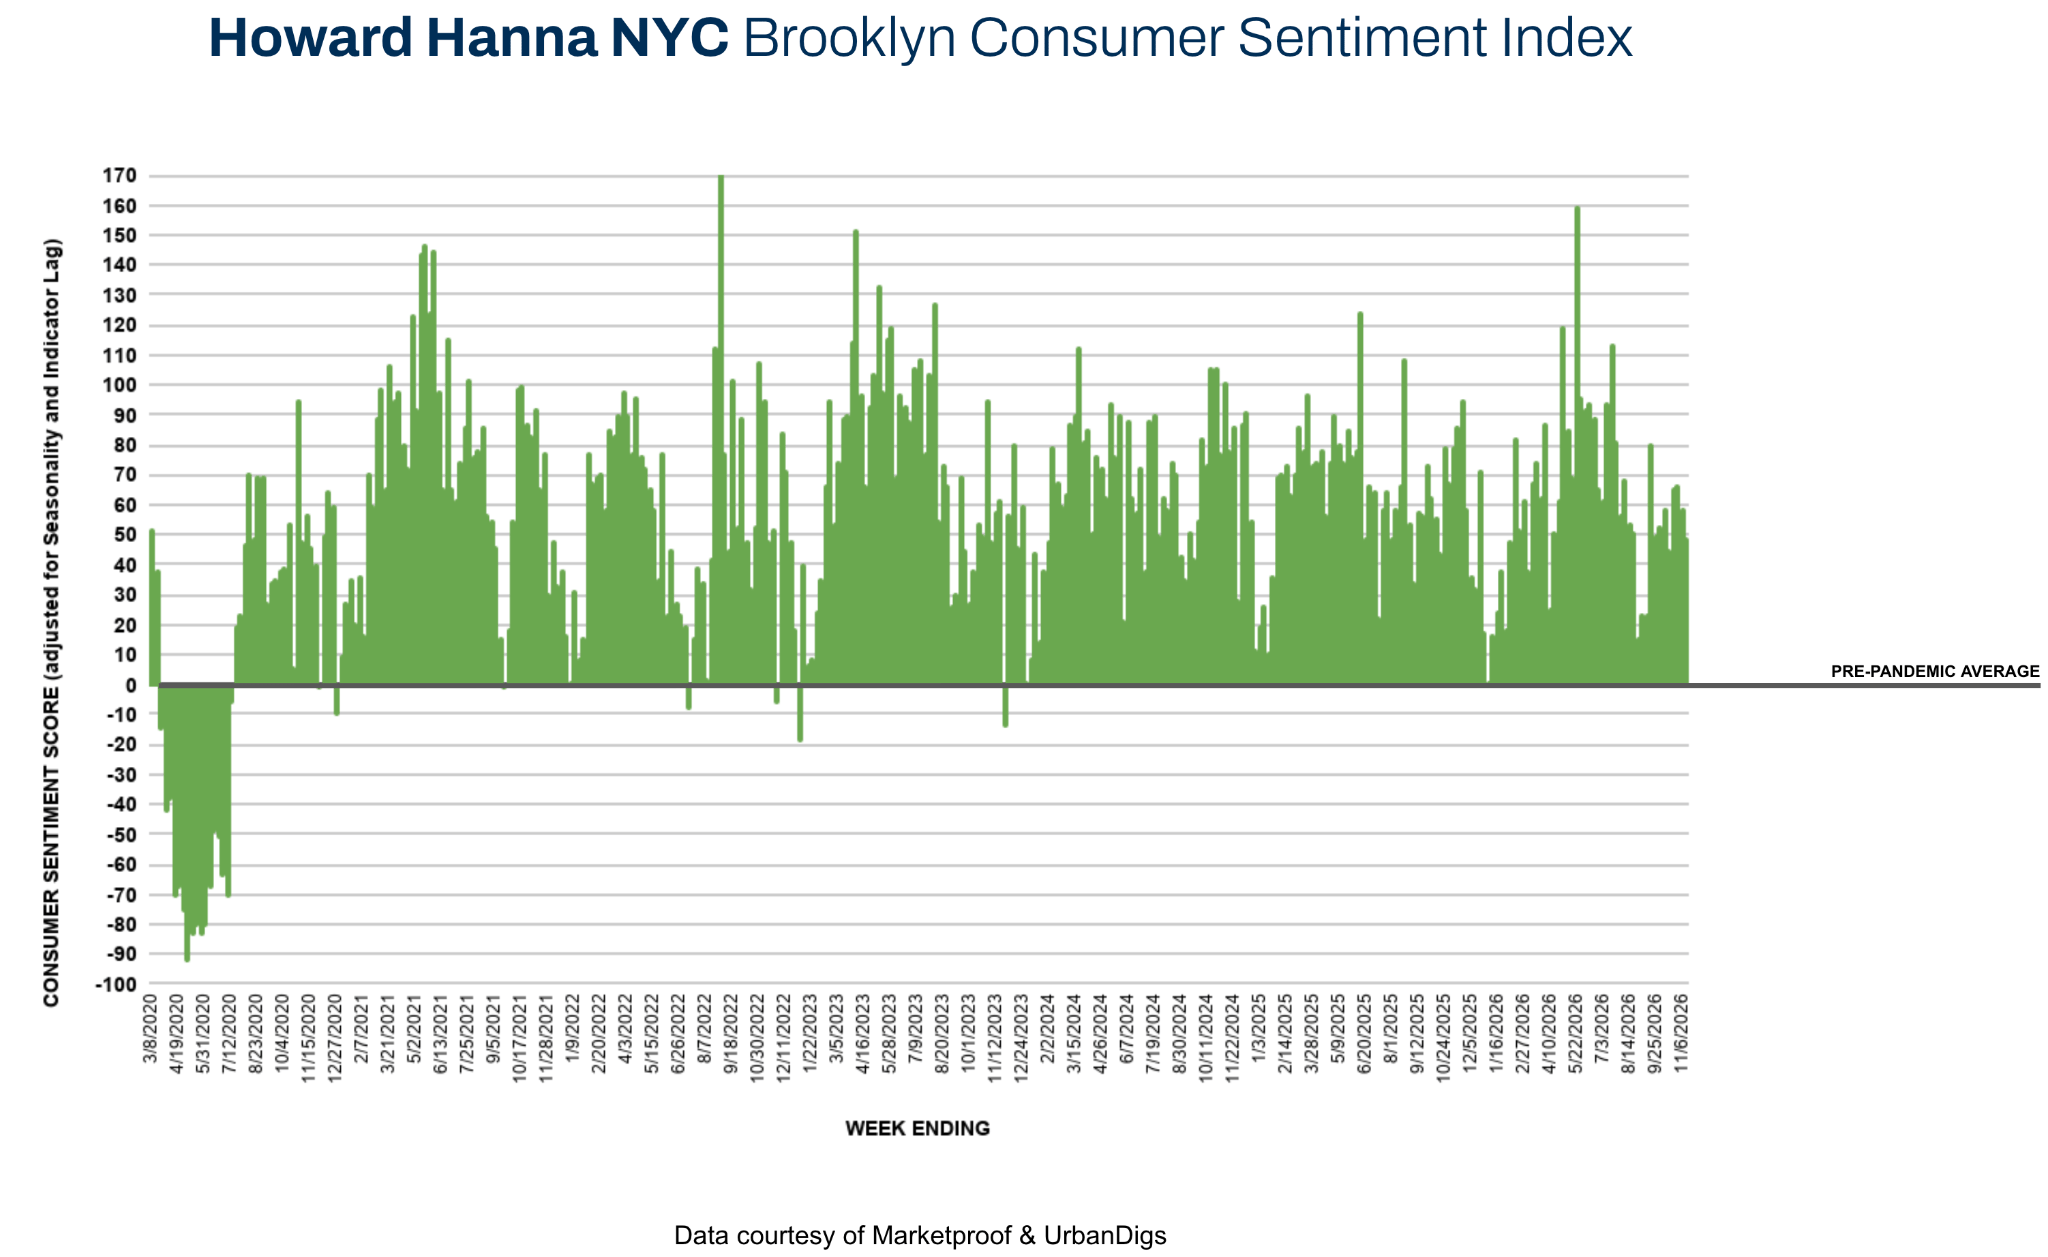
Photo by Rihards Gederts | Howard Hanna NYC
New Development Insights: Astoria Leads the Busiest Week of the Fall
According to Marketproof data, new development activity recorded 35 signed contracts across 27 buildings during the week of November 9, 2026, up from 29 the prior week and the busiest week of the fall. Top-performing developments included:
- The Rowan II (Astoria-Ditmars) with three signed contracts
- The Marina Astoria (Astoria) with three signed contracts
Astoria takes both top spots, and The Rowan II leads the board for a second straight week. While resale contracts cooled this week, sponsor activity moved the other way, with more buildings signing deals than in any week this fall.
Note: weekly new development tallies are reported with a lag, so figures may be revised as late-reported contracts post after the week closes.
Click HERE to review this week’s activity on Marketproof.
If you would like to chat about the most recent market activity,
feel free to contact us at [email protected] or connect with one of our Advisors.
Howard Hanna NYC brings the nation’s largest independent and family-owned brokerage to New York City, uniting the strength of a national network with the insight and sophistication of a local firm. Formed through joining forces with Elegran Real Estate, Howard Hanna NYC delivers a seamless, full-service experience backed by more than 15,000 agents across 500 offices in 14 states. The firm’s forward-thinking, agent-first culture continues to shape the future of real estate across Manhattan and the Tri-State area. Learn more at www.howardhannanyc.com.