Fall’s Third Week: The Shelf Refills Faster Than Buyers Sign
Three weeks into the fall market, the two halves of the story are moving in opposite directions. Supply kept building: Manhattan inventory rose a third straight week to 5,829 homes, its highest level since late July, and Brooklyn climbed to 3,741, now 5.1% above last year. But demand stepped back after last week’s rebound. Manhattan logged 113 signed contracts, its fewest in any week since New Year’s, and both boroughs’ pending pipelines slipped again.
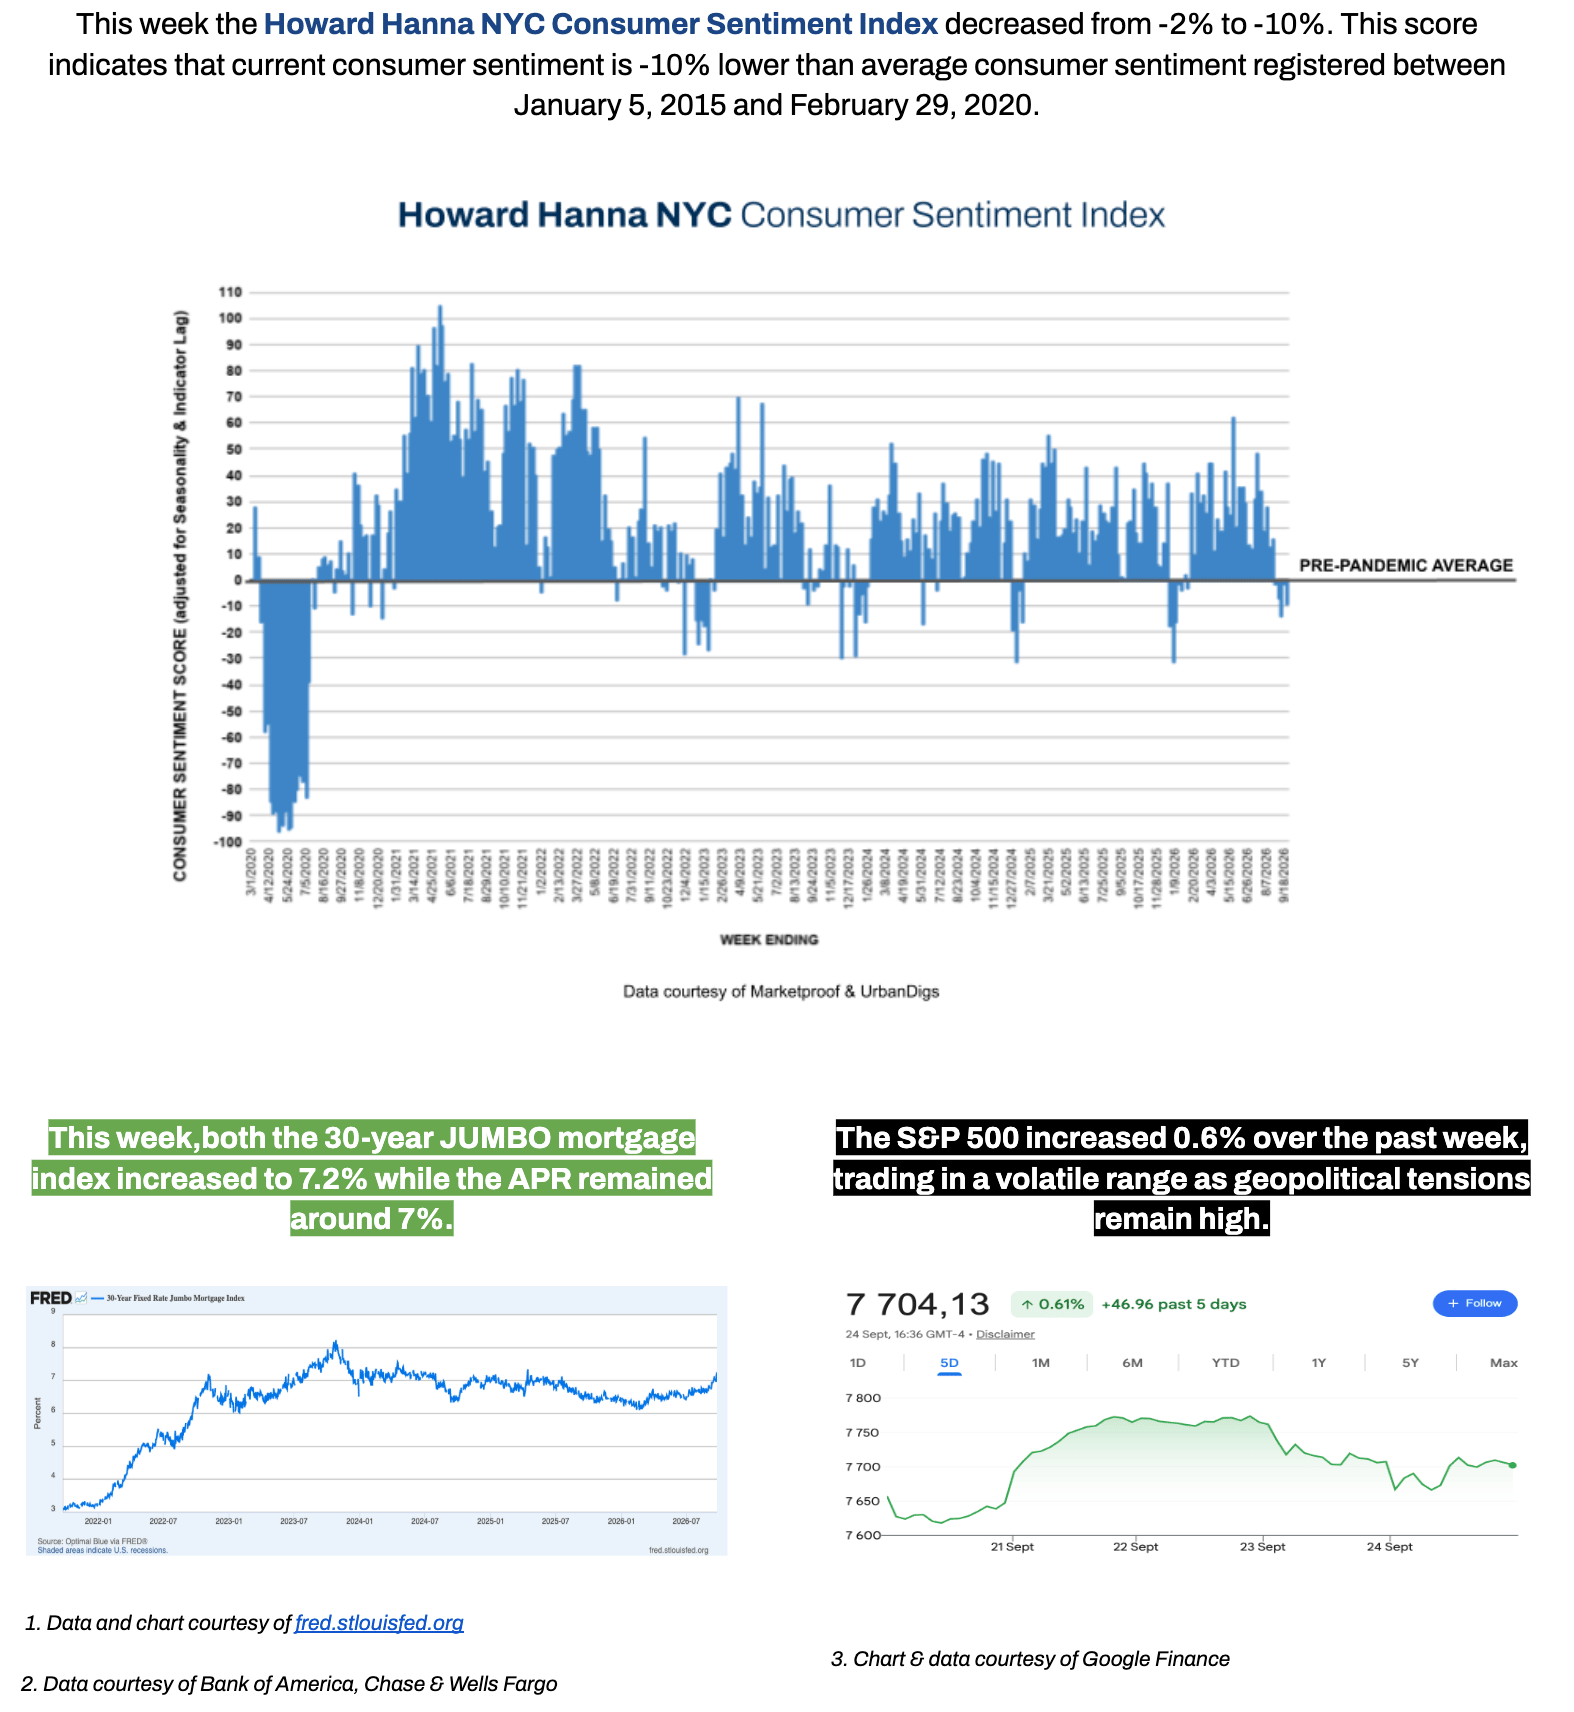
The Howard Hanna NYC Consumer Sentiment Index decreased from −2% to −10%. With 1,521 new Manhattan listings and 850 in Brooklyn over the past three weeks, the fall restock has arrived in full; the question now is how quickly buyers work through it.
What This Means for Fall 2026
For buyers: This is the best-positioned week of the year to be a Manhattan buyer. Selection is the deepest since midsummer, contract activity is at a nine-month low, and sellers who launched into the September wave are now watching their listings sit alongside hundreds of others. That combination opens room to negotiate that simply did not exist in August. In Brooklyn, demand is cooler than last week but still firmly positive, so the best homes there will still move quickly.
For sellers: The window of scarcity pricing has closed for now in Manhattan. With inventory up more than 1,400 homes in three weeks and buyers signing at a slower pace, the listings that stand out will be the ones priced to the most recent comps, not to last spring’s. Sellers still preparing to launch this fall should weigh a sharp opening price over the hope of a bidding war.
Overall, the market has shifted from a supply story to a demand test. Manhattan’s year-over-year inventory deficit has narrowed from 24% to 12% in three weeks, and Brooklyn has moved from a deficit to a surplus. The calendar explained much of the early-September softness in contracts; three weeks past Labor Day, the gap is harder to attribute to timing alone. The next two to three weeks will show whether buyers are simply taking their time with a deeper selection, or holding back in a 7% jumbo-rate environment.
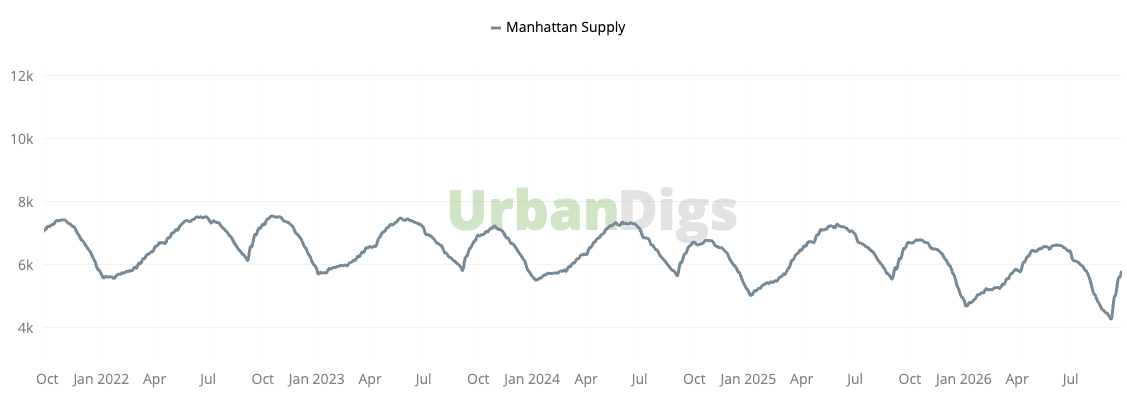
Manhattan Supply: A Third Straight Increase Takes Inventory to a Two-Month High
Manhattan active inventory rose to 5,829 homes (+7% week-over-week | −12% year-over-year), a third consecutive weekly increase and the highest count since late July. New listings totaled 418 units (−25% week-over-week | +5% year-over-year), cooling from the two record weeks before it but still running ahead of last year’s pace.
The deficit that defined this cycle is closing quickly: from 24% below last year at the start of September to 12% today. The shelf is not yet oversupplied, but it is no longer empty, and with contracts slowing, standing inventory is now accumulating rather than being absorbed as fast as it arrives.
Brooklyn Supply: 5% Above Last Year and the Highest Since June
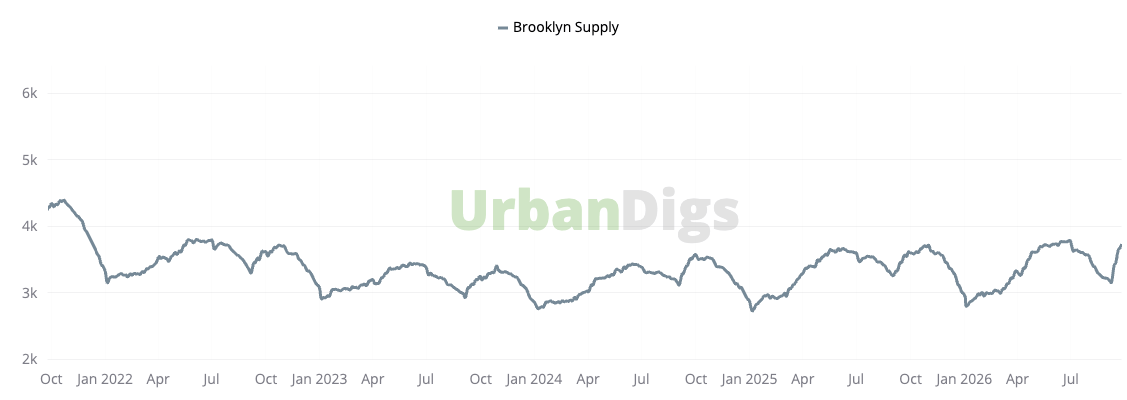
Brooklyn inventory rose to 3,741 homes (+4% week-over-week | +5.1% year-over-year), a third straight weekly gain and the borough’s highest level since late June. New listings totaled 233 units (−28% week-over-week | +10% year-over-year), easing from last week’s 2026 high while still running comfortably above last September.
Brooklyn has swung from a 2.8% deficit to a 5.1% surplus in three weeks. For buyers, that means genuine choice across most neighborhoods; for sellers, it means presentation and pricing now carry more weight than timing.
Pending Sales: Pipelines Still Waiting on the Fall Rebuild
Both pipelines declined again this week, a fifth straight weekly decline in Manhattan and a sixth in Brooklyn, with Manhattan posting its steepest drop since the Labor Day reset. Summer deals are still rolling to closing faster than new contracts replace them, which leaves the fall rebuild still ahead.
• Manhattan pending sales: down −5% week-over-week to 2,866 units, the lowest level since early March.
• Brooklyn pending sales: down −1% week-over-week to 1,834 units, a milder decline that leaves the pipeline at its lowest since early May.
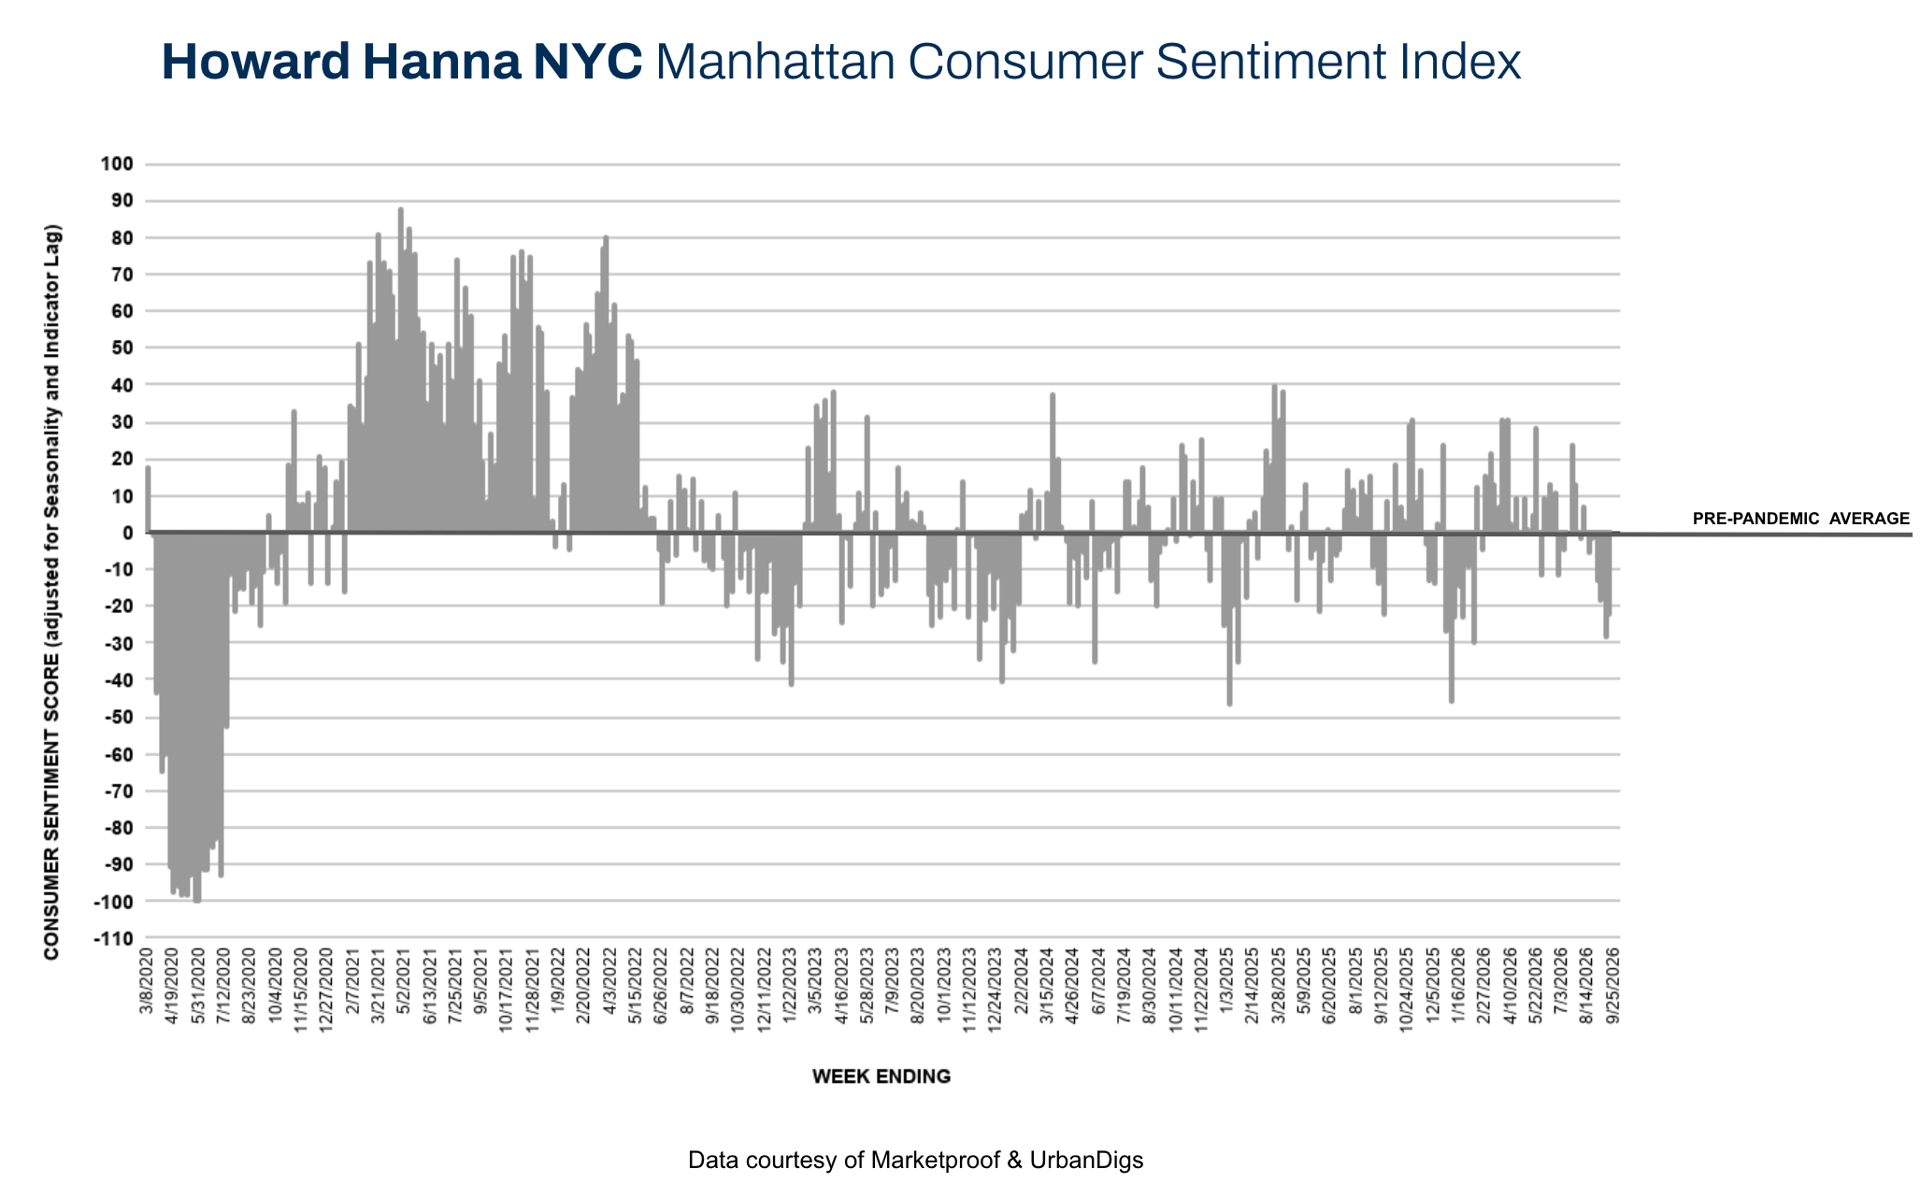
Manhattan Consumer Sentiment: The Softest Demand Since New Year’s
Manhattan recorded 113 signed contracts (−14% week-over-week | −37% year-over-year), the fewest in any week since the first week of January, as last week’s rebound failed to carry through.
The Howard Hanna NYC Manhattan Consumer Sentiment Index decreased from −23% to −32%. Rising supply and slowing contracts together push this gauge lower, and this week delivered both. It is a buyer’s window rather than a verdict on the season: the late-September and October weeks, when the full fall buyer pool is back, will show whether demand catches up with the new inventory.
Brooklyn Consumer Sentiment: Cooling From the Peak, Still Firmly Positive
Brooklyn recorded 108 signed contracts (−4% week-over-week | −14% year-over-year), holding close to last week’s strong level.
The Howard Hanna NYC Brooklyn Consumer Sentiment Index decreased from +80% to +50%, giving back part of last week’s surge while remaining well above its pre-pandemic average. Brooklyn continues to be the steadier of the two boroughs: demand there has held up even as supply moved to a year-over-year surplus.
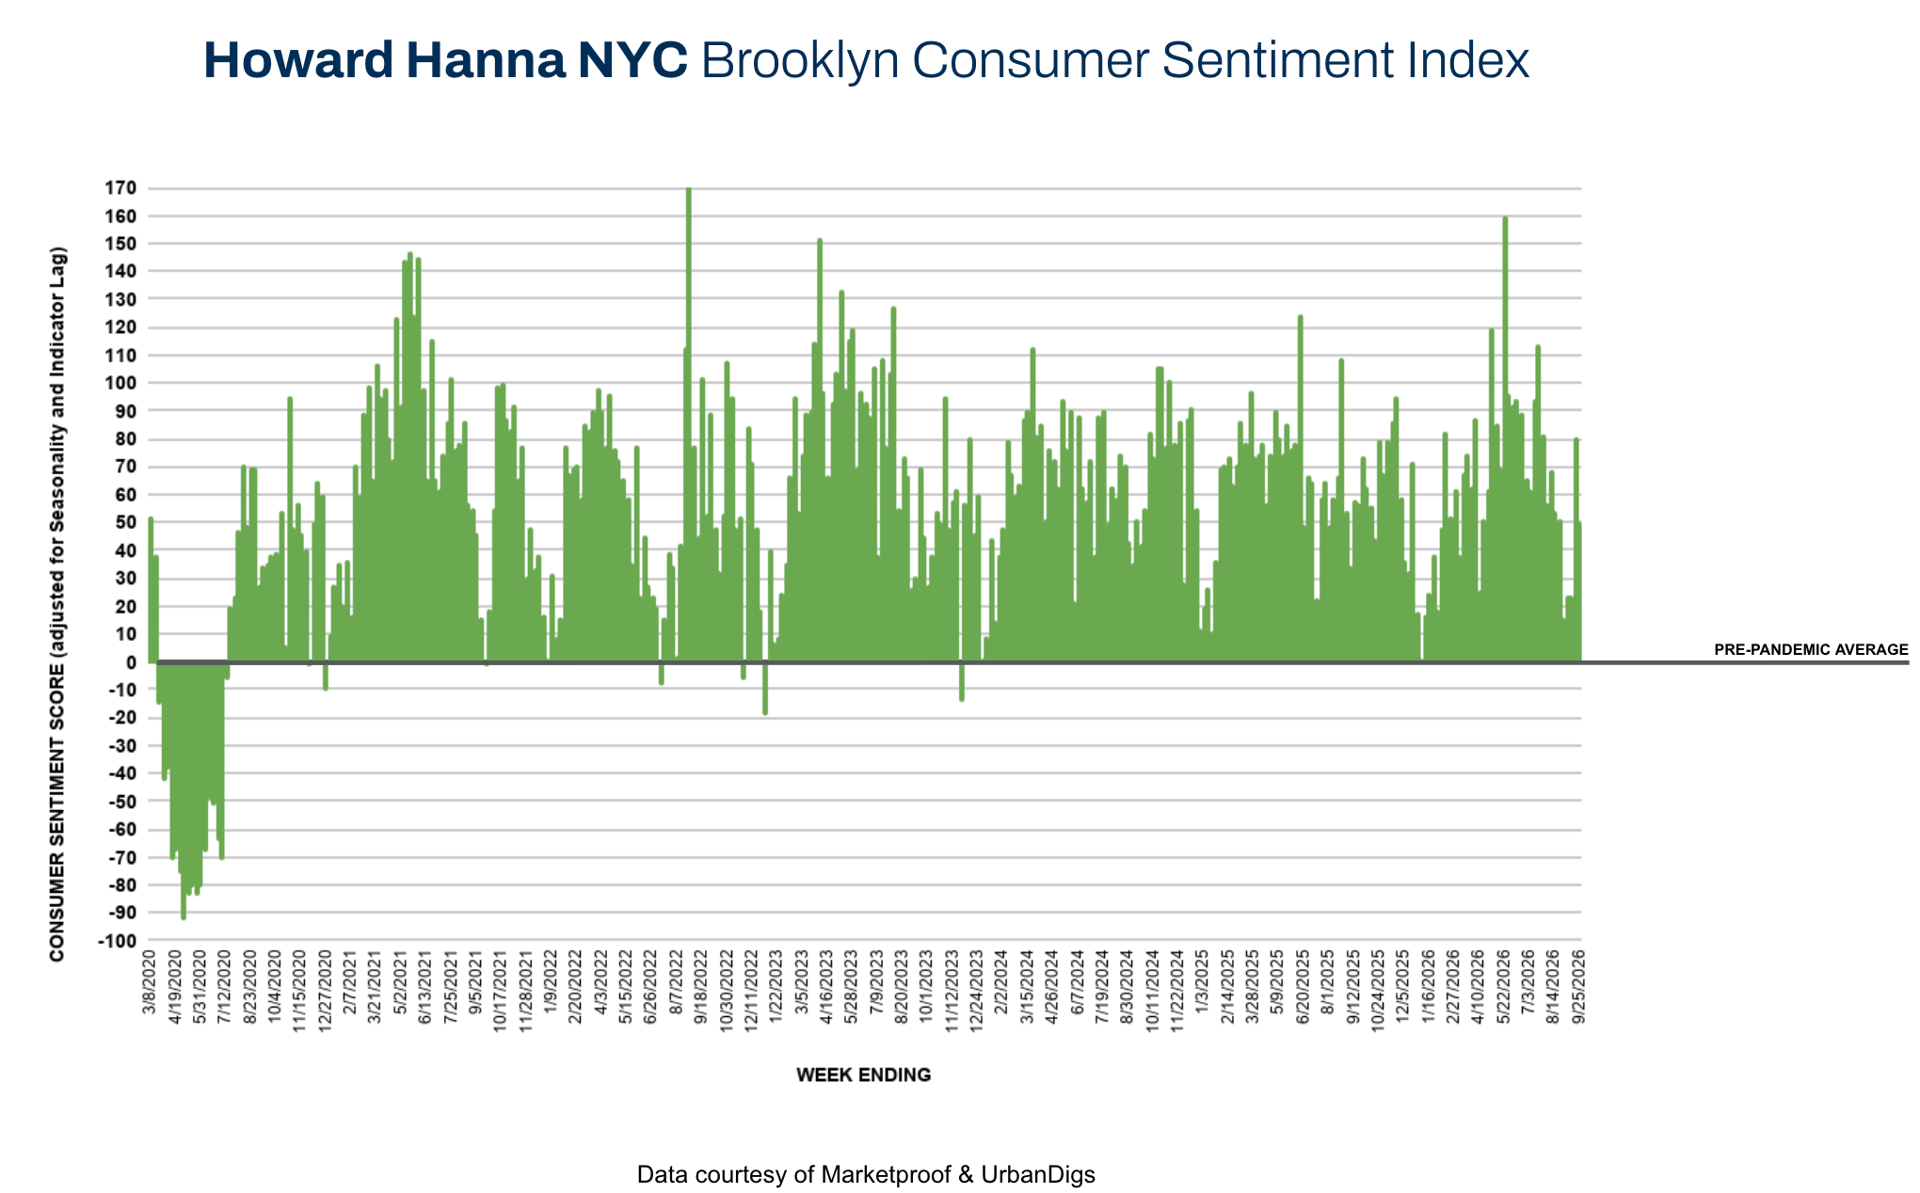
Photo by Rihards Gederts | Howard Hanna NYC
New Development Insights: The Emmet Building Posts a Standout Week in NoMad
According to Marketproof data, new development activity recorded 31 signed contracts across 23 buildings during the week of September 21, 2026. Top-performing developments included:
• The Emmet Building (NoMad) with six signed contracts
• 717 Grand Street (East Williamsburg) with three signed contracts
Six contracts at a single building is triple the top tally of any development in the previous five weeks, a sign that well-positioned fall launches can still draw concentrated demand even as the resale market softens. 717 Grand Street keeps a Brooklyn name near the top of the board.
Note: weekly new development tallies are reported with a lag, so figures may be revised as late-reported contracts post after the week closes.
If you would like to chat about the most recent market activity,
feel free to contact us at [email protected] or connect with one of our Advisors.
Howard Hanna NYC brings the nation’s largest independent and family-owned brokerage to New York City, uniting the strength of a national network with the insight and sophistication of a local firm. Formed through joining forces with Elegran Real Estate, Howard Hanna NYC delivers a seamless, full-service experience backed by more than 15,000 agents across 500 offices in 14 states. The firm’s forward-thinking, agent-first culture continues to shape the future of real estate across Manhattan and the Tri-State area. Learn more at www.howardhannanyc.com.