November 2026 EDITION - DATA THROUGH October 2026
Manhattan Market Pulse ¹ November 2026
Metric | Value | vs Prior Year | vs Prior Month | Favors |
|---|---|---|---|---|
Demand (Contracts Signed) | 916 in October | ↓-9.4% | ↑+56.0% | SELLERS |
Median Listing Discount | 4.5% in October | ↑+0.1 pts | ↑+0.7 pts | BUYERS |
Median PPSF | $1,428 in October | ↑+7.3% | ↓-0.3% | SELLERS |
Sales Over Ask | 14.6% in August | ↑+2.6 pts | ↓-3.5 pts | SELLERS |
Supply | 6,097 in October | ↓-9.0% | ↑+1.7% | NEUTRAL |
Median Sale Price | $1.28M in October | ↑+14.9% | ↑+3.0% | SELLERS |
Median Days on Market | 83 in October | ↑+1.2% | ↑+6.4% | BUYERS |
Arrows show direction only: green = up, red = down. “Sales Over Ask” lags an additional month; all other rows reflect October 2026. Data courtesy of UrbanDigs.
MEDIAN SALE PRICE BY BEDROOM, ALL MANHATTAN (OCTOBER, BY CLOSED DATE)
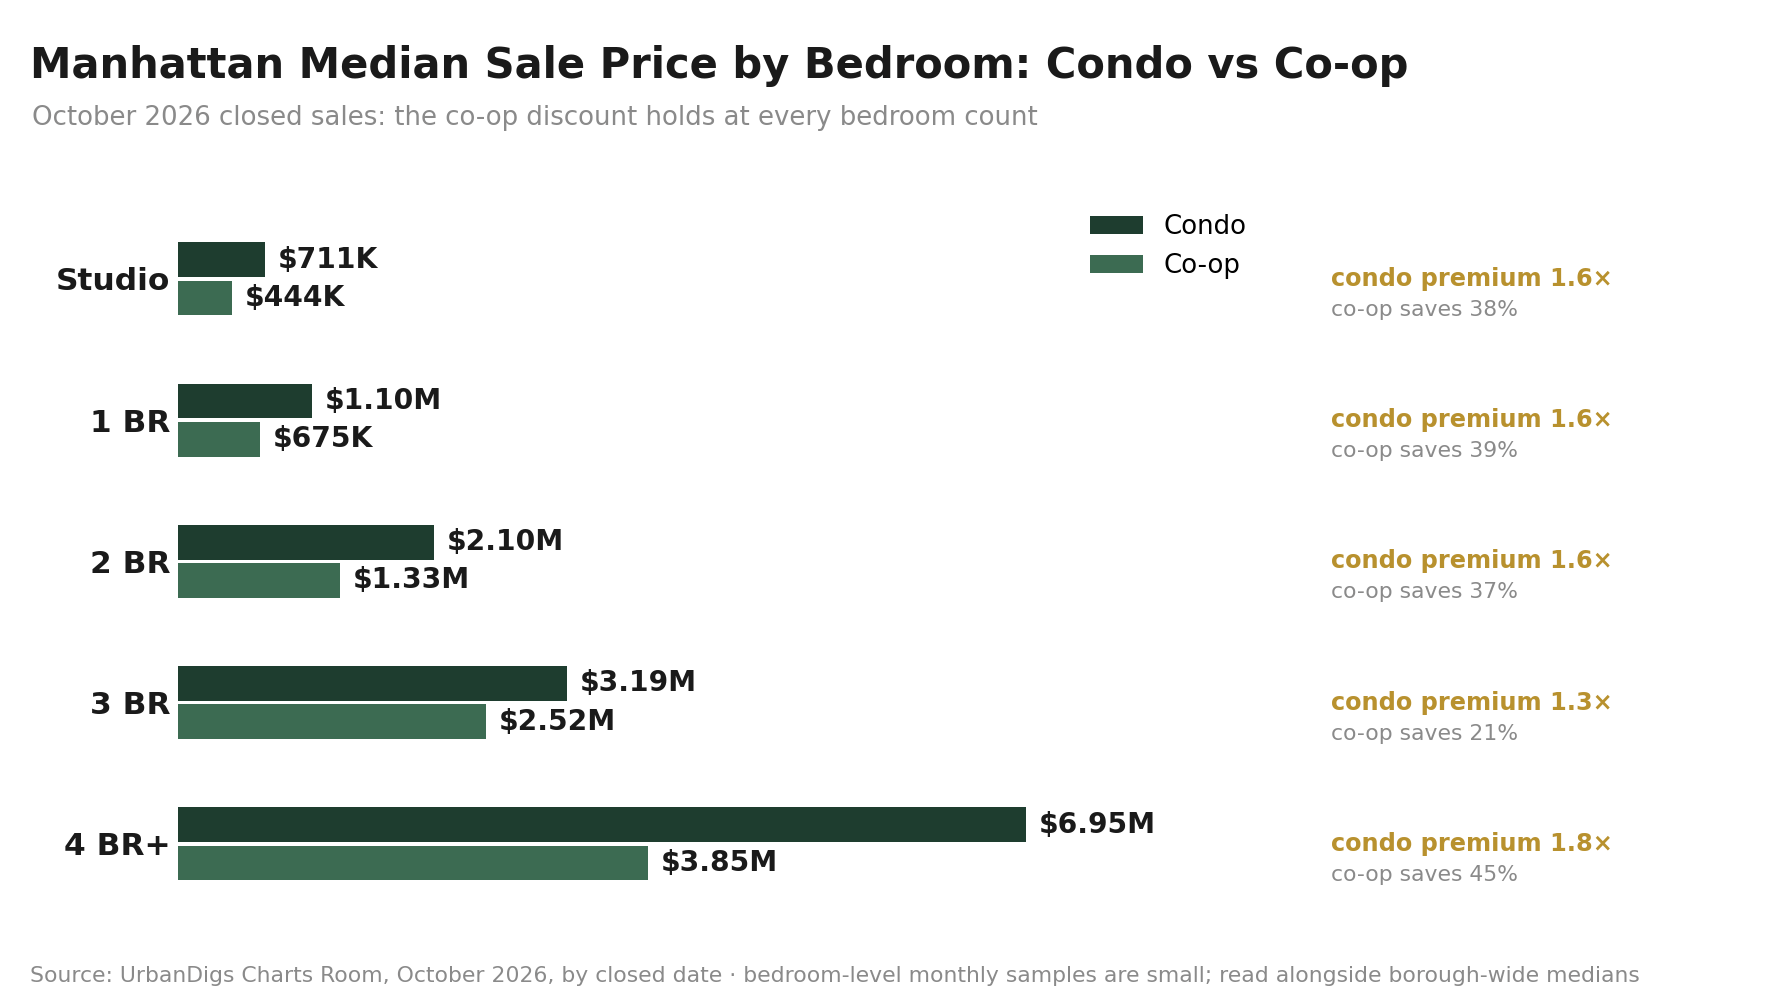
Buyers Come Back: Contracts Jump 56% as Prices Hold Firm
October answered the question September raised. Buyers signed 916 contracts, up 56% from September though still 9% below last October, and the Market Pulse moved back above seasonal norms. Supply held near 6,100 listings as new listings slowed. Prices stayed firm: the median sale price is $1.28M and price per square foot is up 7% on the year. Negotiating room widened, with the median discount at 4.5%, so deals are getting done at the right price, not at any price.
Bottom line: demand is back and prices are firm, but buyers who negotiate are getting deals done. Well-priced homes sell; overpriced ones sit and cut.
Market Snapshot: Five Numbers That Matter
- 916 contracts signed, up 56% from September and 9% below last October.
- $1.28M median sale price, up 15% year over year.
- 4.5% median listing discount, the widest since March.
- 6,097 active listings, still 9% below last year.
- 2,926 pending sales, 5% ahead of last year.
Key Takeaways
- The September dip was seasonal: the Market Pulse is back above seasonal averages.
- Sellers are pulling back: new listings fell 32% from September, so the fall wave is cresting.
- By bedroom: condo 4BR+ is up 24% on the year while condo 3BRs are down 13%; co-op prices are steady at every size.
Outlook
November and December are seasonally quieter, and the Fed meets December 8–9 with markets pricing a hike. If the 10-year stays below 5%, expect steady contract activity into year-end; if it rebounds, price cuts will do more of the work.
For Sellers: Demand is there, but buyers expect a discount. Price within reach of recent comparables and the right buyer will meet you.
For Buyers: Competition is back, and so is negotiating room. Focus on listings that have sat; homes past 120 days negotiate around 9%.
Howard Hanna NYC Manhattan Leverage Index
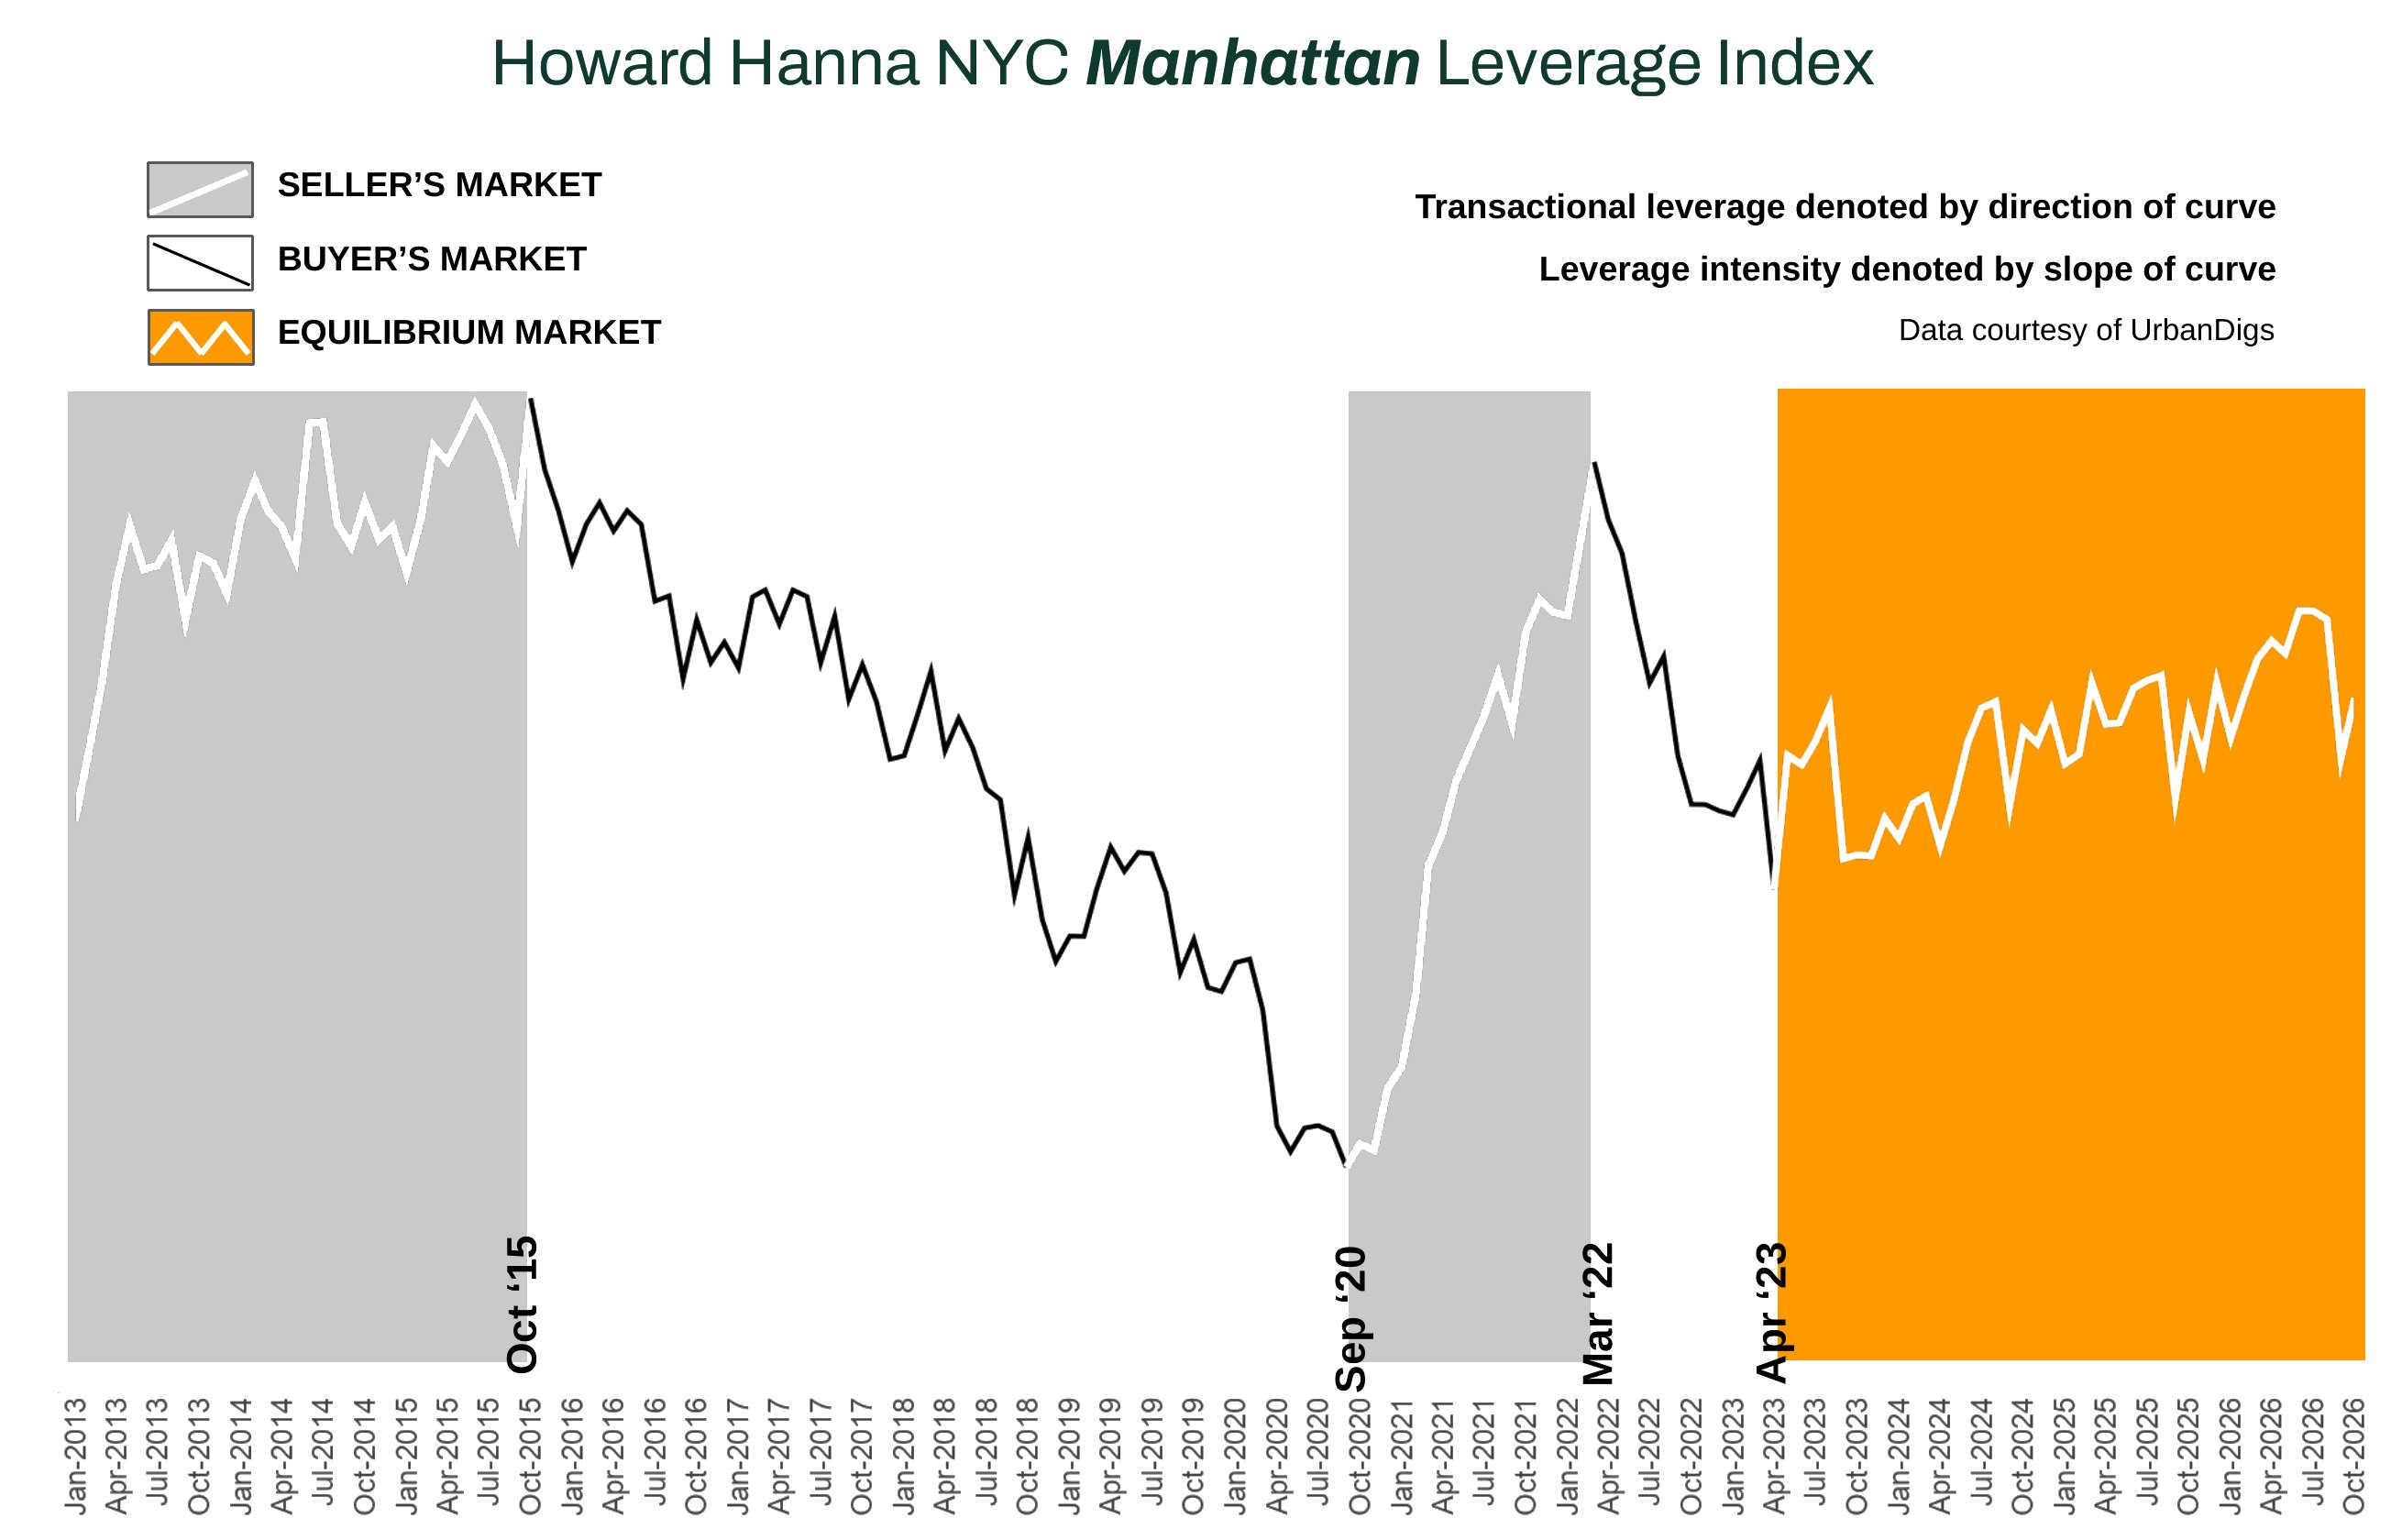
The Howard Hanna NYC Manhattan Leverage Index blends four signals, supply, demand, median PPSF and listing discount, into one reading of who holds the leverage. Tightening supply, rising demand, firming PPSF and shrinking discounts point to sellers; the reverse points to buyers.
Signal | October 2026 Reading | Points To |
|---|---|---|
Supply | 6,097 listings, up 2% MoM and 9% below last year | NEUTRAL |
Demand | 916 contracts, up 56% MoM; Market Pulse above seasonal | SELLERS |
Median PPSF | $1,428, up 7.3% YoY | SELLERS |
Listing Discount | 4.5%, up 0.7 pts MoM | BUYERS |
The index rebounded to 0.44 from 0.22, confirming that September's drop was seasonal, as it was in 2023 and 2025. Contracts drove the move, and per-foot pricing still favors sellers; the wider 4.5% discount is the input pointing to buyers. Manhattan remains in equilibrium, with leverage edging back toward sellers. Source: Howard Hanna NYC Leverage Index 2026, data courtesy of UrbanDigs.
Manhattan Supply
6,097 | ↓-9.0% | ↑+1.7% | NEUTRAL |
active listings in October | vs prior year | vs prior month | Favors? |
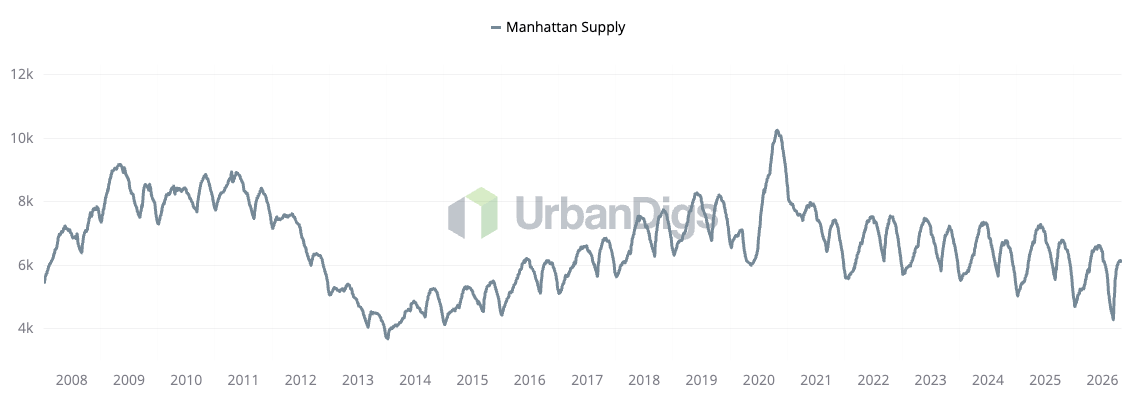
Data & chart courtesy of UrbanDigs.
SUPPLY STEADIES AS NEW LISTINGS SLOW
Active listings edged up to 6,097 in October, still 9% below last year. New listings fell to 1,315, down 32% from September's surge, so the fall wave is cresting.
Buyers: Selection is the best since spring. Use it to compare before you commit.
Sellers: Fewer new competitors are coming. Well-presented listings now stand out.
Manhattan Demand
916 | ↓-9.4% | ↑+56.0% | SELLERS |
contracts signed in October | vs prior year | vs prior month | Favors? |
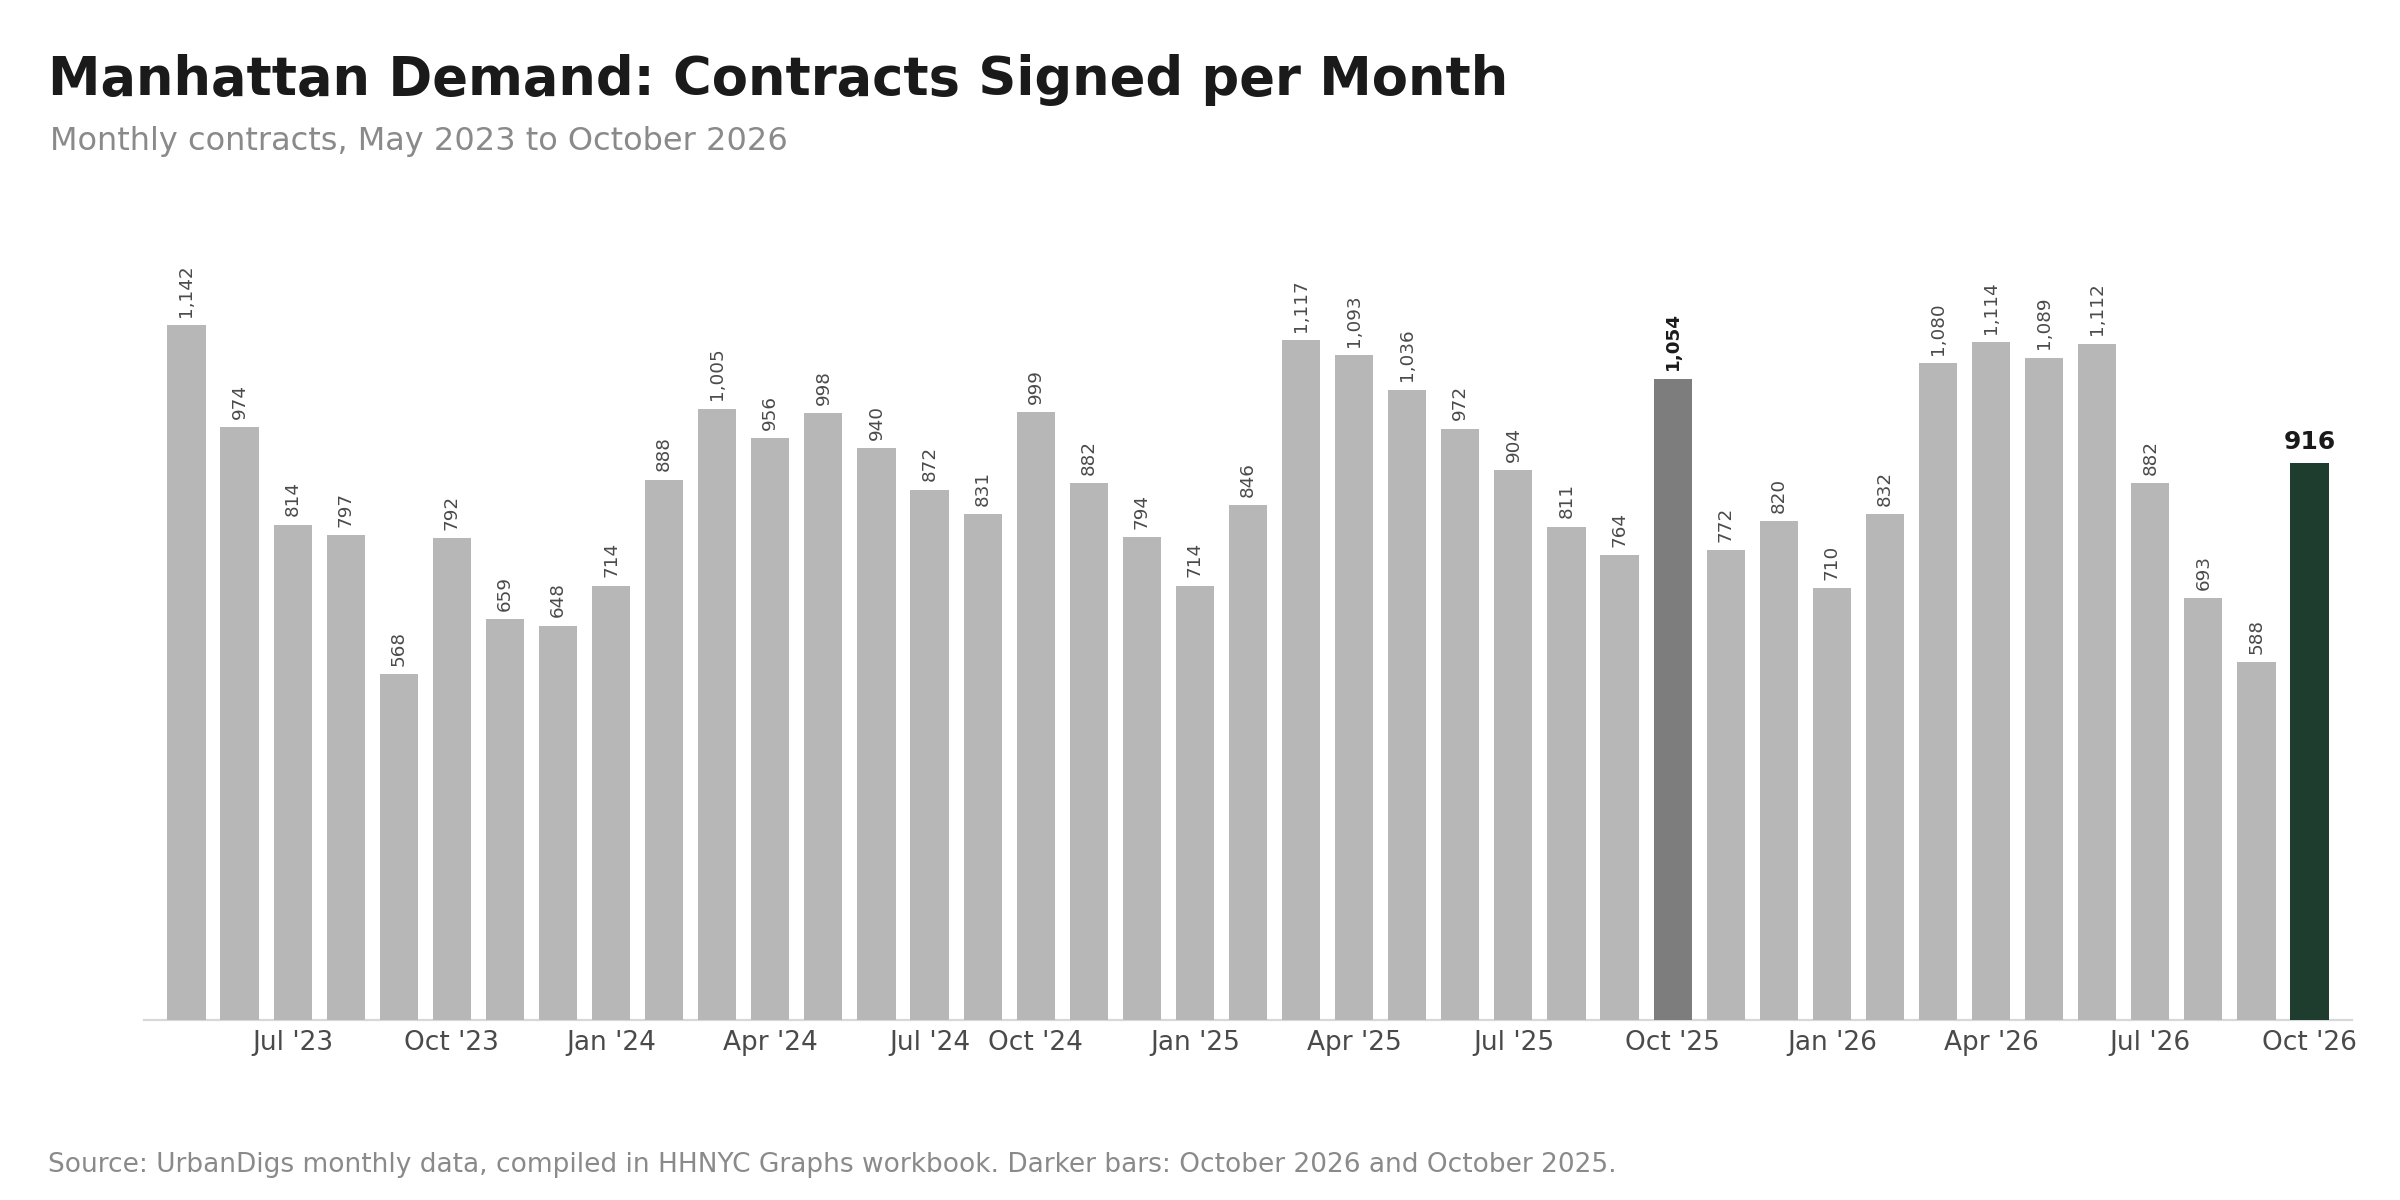
CONTRACTS JUMP 56% FROM SEPTEMBER
Buyers signed 916 contracts in October, up 56% from September and 9% below last October. The Market Pulse moved back above seasonal averages, and pending sales are 5% ahead of last year.
Buyers: Competition is back on the best listings. Be ready to move.
Sellers: Buyers are active again. Price right and you will get showings.
Manhattan Median PPSF
$1,428 | ↑+7.3% | ↓-0.3% | SELLERS |
median price per square foot in October | vs prior year | vs prior month | Favors? |
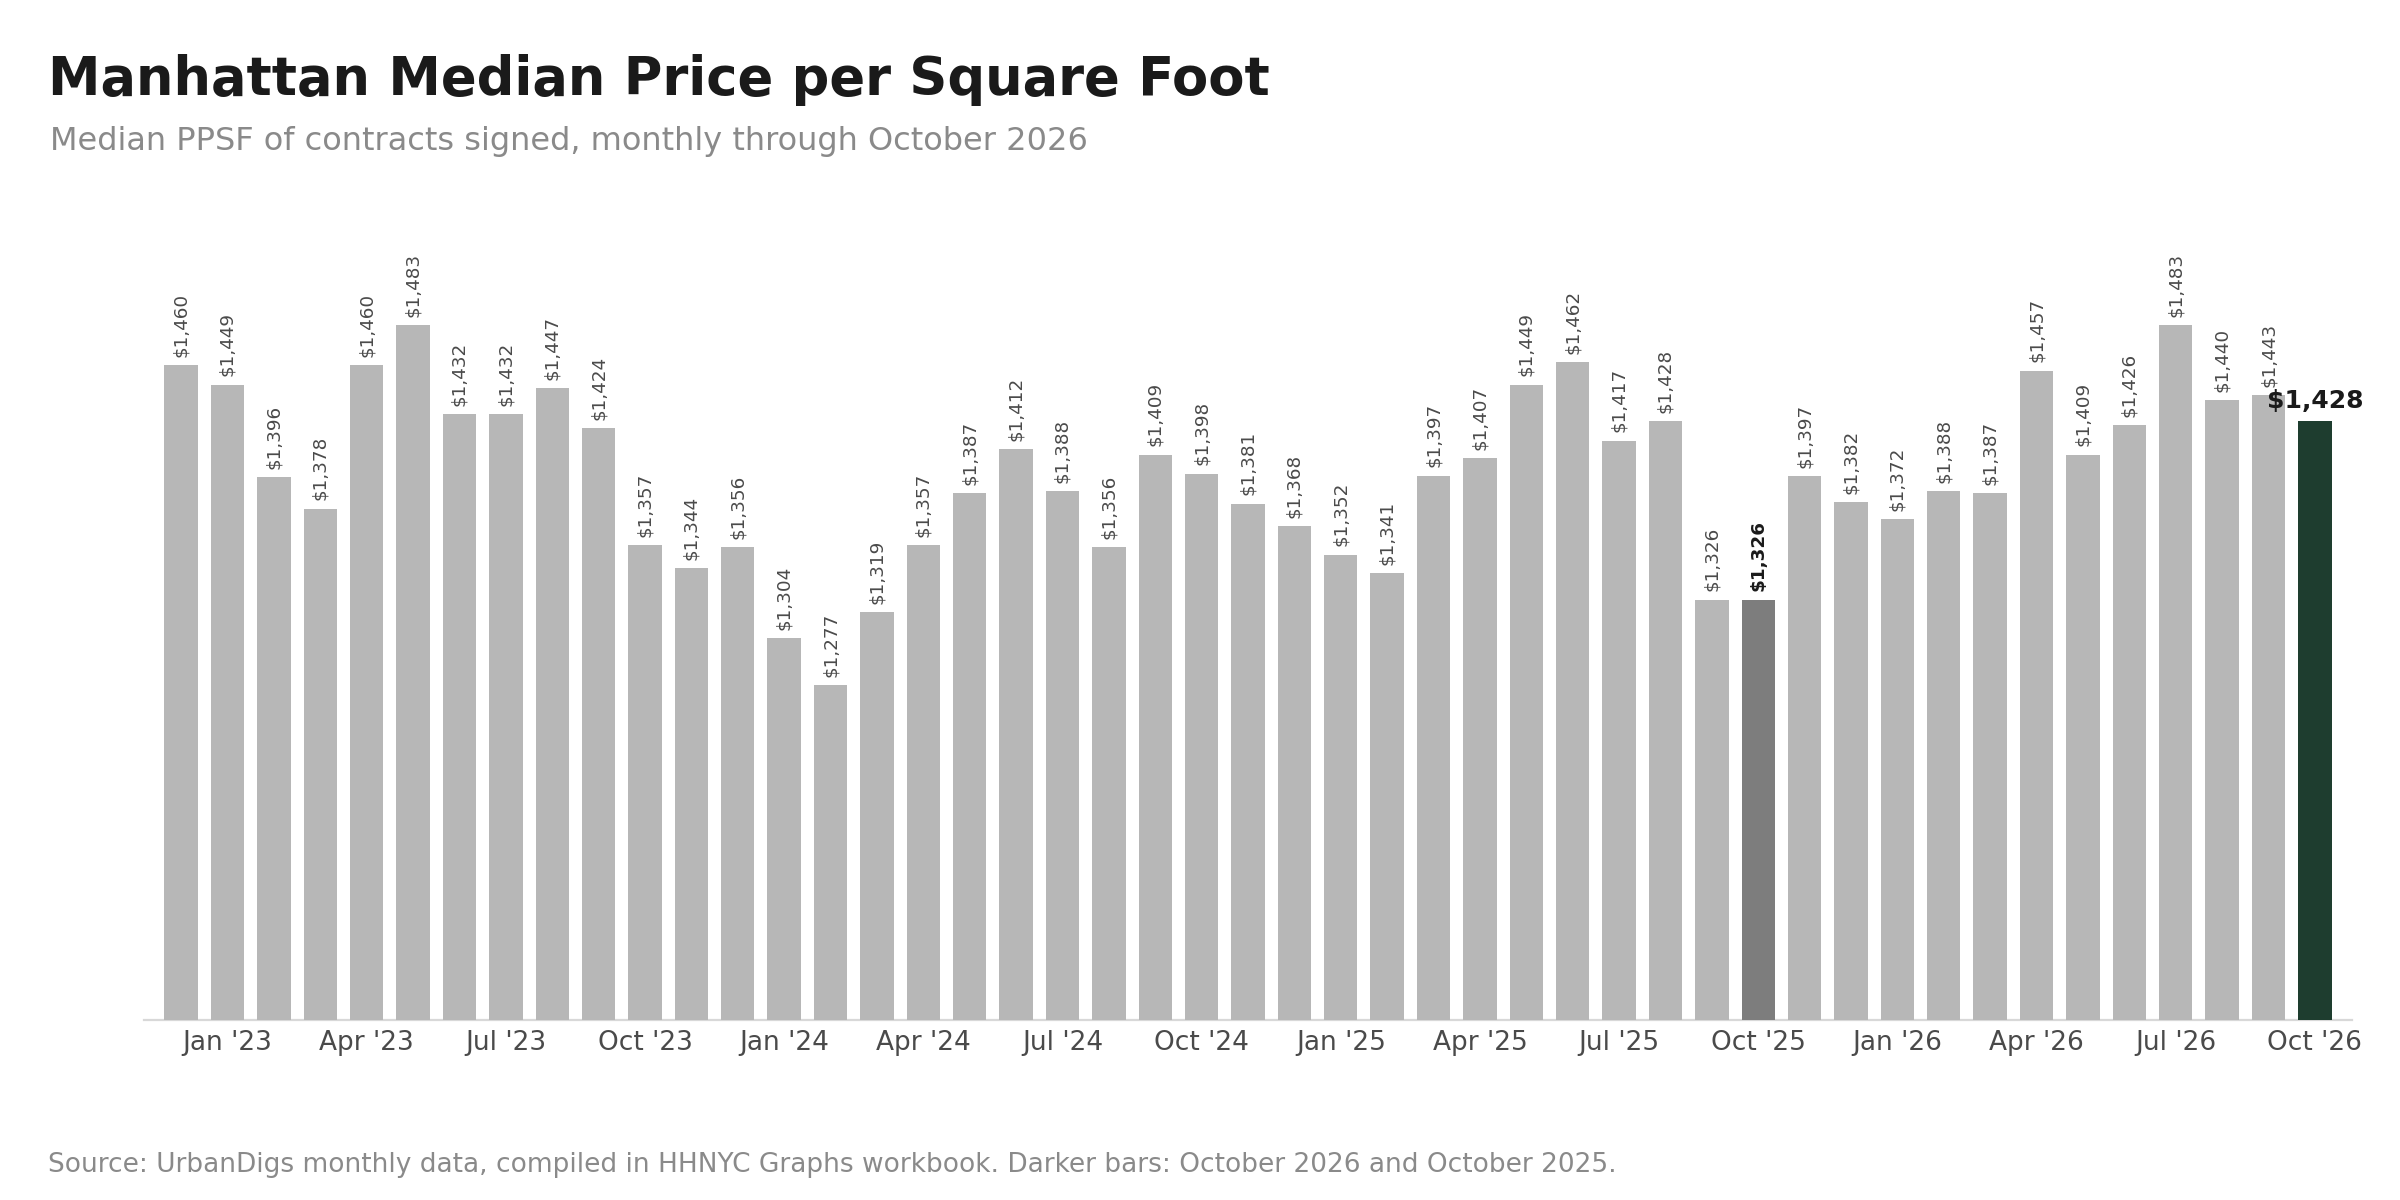
PER-FOOT PRICING HOLDS NEAR 2026 HIGHS
Median PPSF was $1,428, flat on the month and up 7% on the year. The homes that trade are well located and well priced, which keeps per-foot values firm.
Buyers: Per-foot prices are not falling. Your leverage is in terms and the discount.
Sellers: Comparables still support confident pricing for move-in-ready homes.
Manhattan Median Listing Discount
4.5% | ↑+0.1 pts | ↑+0.7 pts | BUYERS |
median listing discount in October | vs prior year | vs prior month | Favors? |
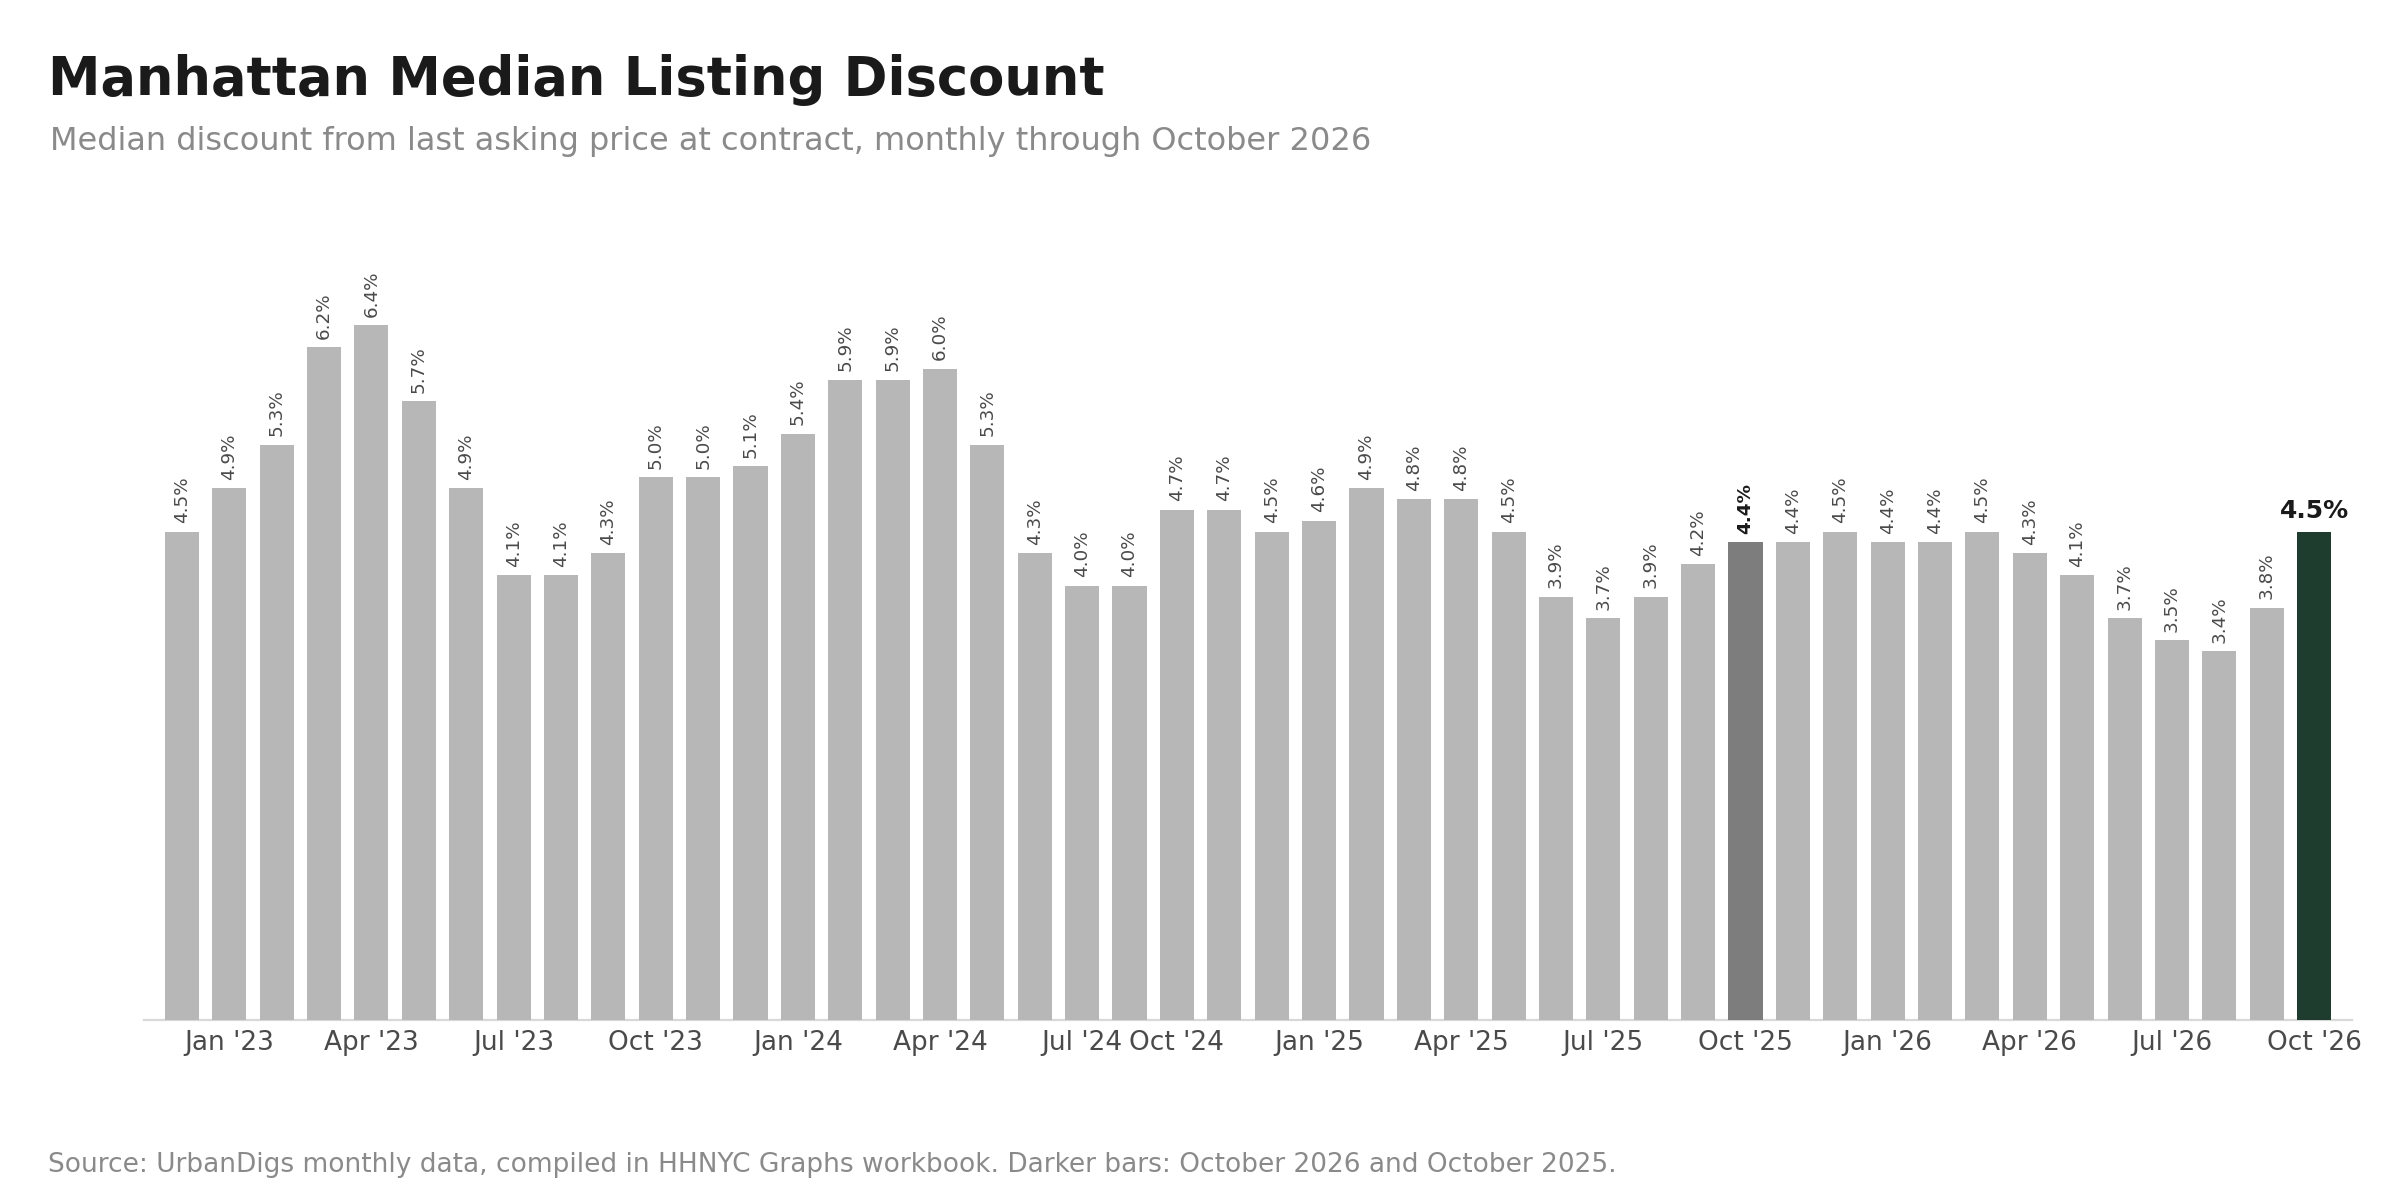
NEGOTIATING ROOM WIDENS TO 4.5%
The median listing discount widened to 4.5% from 3.8% in September, the widest since March. On a $1.5M listing, that is about $68,000 off ask.
Buyers: Ask for more on listings that sat through the fall.
Sellers: Overpricing is expensive. The longer a listing sits, the deeper the discount.
Rental Remarks
RENTS HOLD AT RECORD LEVELS INTO THE FALL
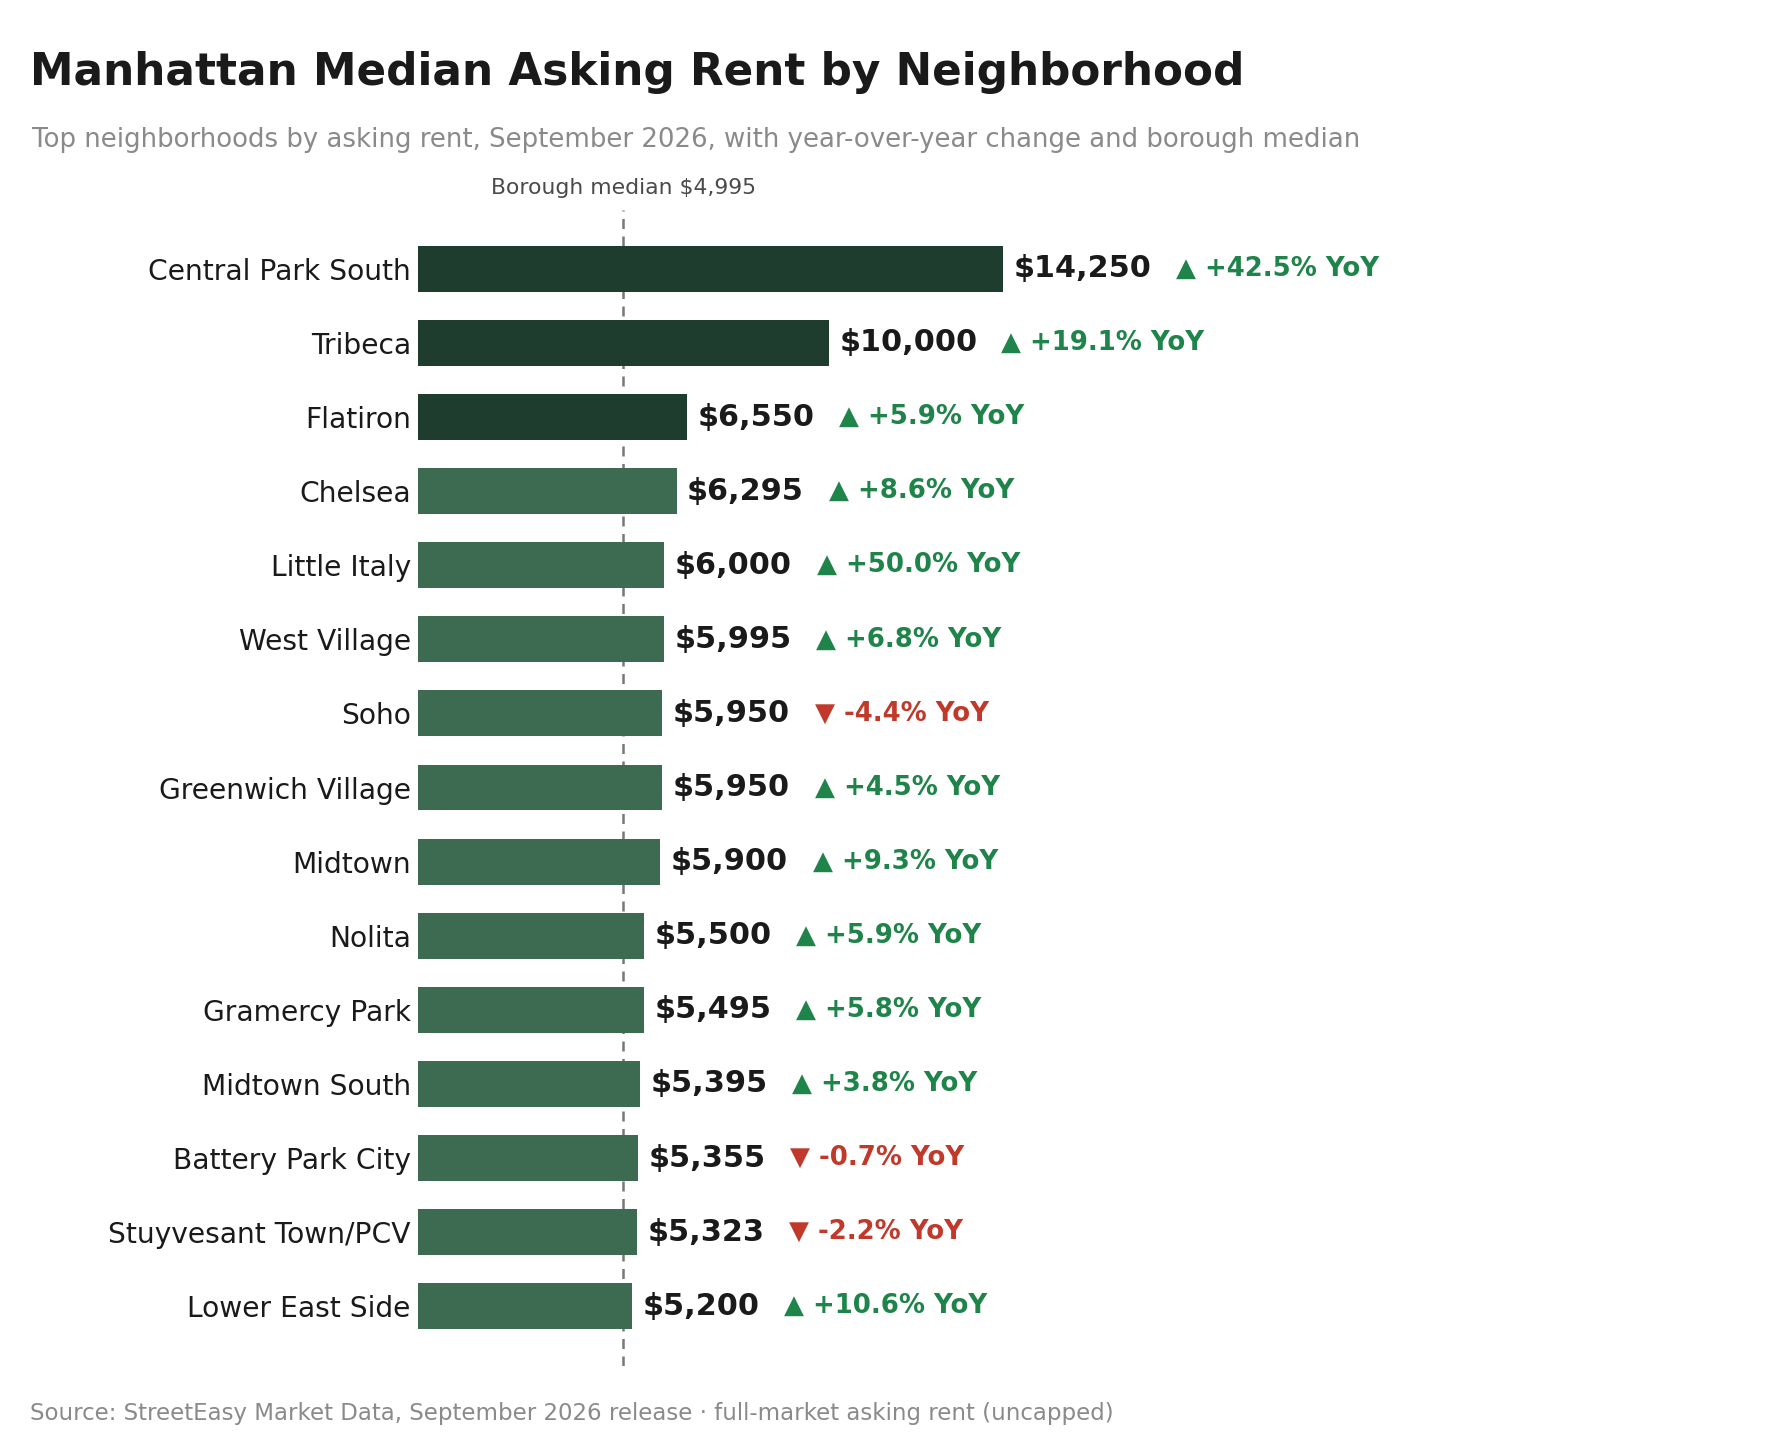
Manhattan's median asking rent held at $4,995 in September, up 8% on the year, per StreetEasy, skipping the usual post-summer dip. Rental inventory fell 16% from last year. Jonathan Miller's closed-lease data shows the same squeeze: a $4,900 median, the second highest on record, with listings down 23%. Since October 1, rent-stabilized renewals are frozen at 0%; market-rate apartments are not affected.
Neighborhood | Asking Sep26 | MoM | YoY | Inventory | Inv YoY | Discount | Disc. YoY |
|---|---|---|---|---|---|---|---|
Central Park South | $14,250 | ↓-5.0% | ↑+42.5% | 53 | ↑+8.2% | 7.5% | ↓-53.8% |
Tribeca | $10,000 | ↑+10.0% | ↑+19.1% | 245 | ↑+3.8% | 12.2% | ↓-19.7% |
Flatiron | $6,550 | ↑+0.8% | ↑+5.9% | 274 | 0.0% | 33.6% | ↓-3.2% |
Chelsea | $6,295 | ↑+1.6% | ↑+8.6% | 612 | ↓-22.1% | 22.7% | ↑+2.6% |
West Village | $5,995 | ↓-3.3% | ↑+6.8% | 454 | ↑+2.5% | 19.2% | ↓-22.8% |
Greenwich Village | $5,950 | ↑+1.7% | ↑+4.5% | 233 | ↓-22.1% | 18.5% | ↓-30.2% |
Soho | $5,950 | ↓-7.0% | ↓-4.4% | 172 | ↓-7.0% | 16.3% | ↓-22.8% |
Midtown | $5,900 | 0.0% | ↑+9.3% | 362 | ↑+0.8% | 21.3% | ↓-5.7% |
Nolita | $5,500 | ↑+4.8% | ↑+5.9% | 160 | ↑+24.0% | 13.1% | ↓-64.0% |
Gramercy Park | $5,495 | 0.0% | ↑+5.8% | 189 | ↓-20.9% | 14.8% | ↓-31.9% |
Midtown South | $5,395 | ↑+1.0% | ↑+3.8% | 238 | ↓-7.4% | 18.9% | ↓-24.1% |
Battery Park City | $5,355 | ↓-3.0% | ↓-0.7% | 159 | ↓-4.8% | 24.5% | ↓-38.9% |
Lower East Side | $5,200 | ↑+4.1% | ↑+10.6% | 407 | ↓-22.3% | 14.7% | ↓-31.0% |
Upper West Side | $5,100 | ↑+2.1% | ↑+5.2% | 1,509 | ↓-17.5% | 21.5% | ↓-26.0% |
Financial District | $5,000 | ↓-1.0% | ↑+3.1% | 793 | ↓-0.4% | 20.7% | ↓-11.5% |
Midtown East | $5,000 | 0.0% | ↑+6.4% | 1,560 | ↓-16.0% | 25.8% | ↓-13.2% |
East Village | $4,995 | ↓-2.1% | ↓-0.1% | 697 | ↓-27.5% | 17.1% | ↓-35.1% |
Midtown West | $4,995 | ↓-0.1% | ↑+7.4% | 1,124 | ↓-14.2% | 20.4% | ↓-21.7% |
Upper East Side | $4,595 | ↑+2.1% | ↑+9.4% | 1,573 | ↓-21.9% | 16.5% | ↓-18.5% |
Morningside Heights | $4,460 | ↓-3.0% | ↓-7.1% | 103 | ↓-23.7% | 35.9% | ↓-4.9% |
Roosevelt Island | $4,295 | ↑+1.8% | ↓-7.6% | 63 | ↓-6.0% | 20.6% | ↓-27.2% |
West Harlem | $3,700 | ↓-5.1% | ↑+0.6% | 68 | ↓-32.0% | 8.8% | ↓-26.5% |
Central Harlem | $3,350 | ↓-4.3% | ↓-4.3% | 600 | ↓-10.0% | 15.0% | ↓-26.4% |
East Harlem | $3,295 | ↓-1.6% | ↑+5.3% | 357 | ↓-18.5% | 17.4% | ↑+10.2% |
Hamilton Heights | $3,250 | ↓-4.3% | ↑+1.6% | 185 | ↓-29.1% | 11.9% | ↓-35.3% |
Washington Heights | $3,137 | ↑+0.4% | ↑+12.0% | 319 | ↓-29.4% | 16.3% | ↑+5.3% |
Inwood | $2,995 | 0.0% | ↓-4.2% | 102 | ↓-48.0% | 10.8% | ↑+51.0% |
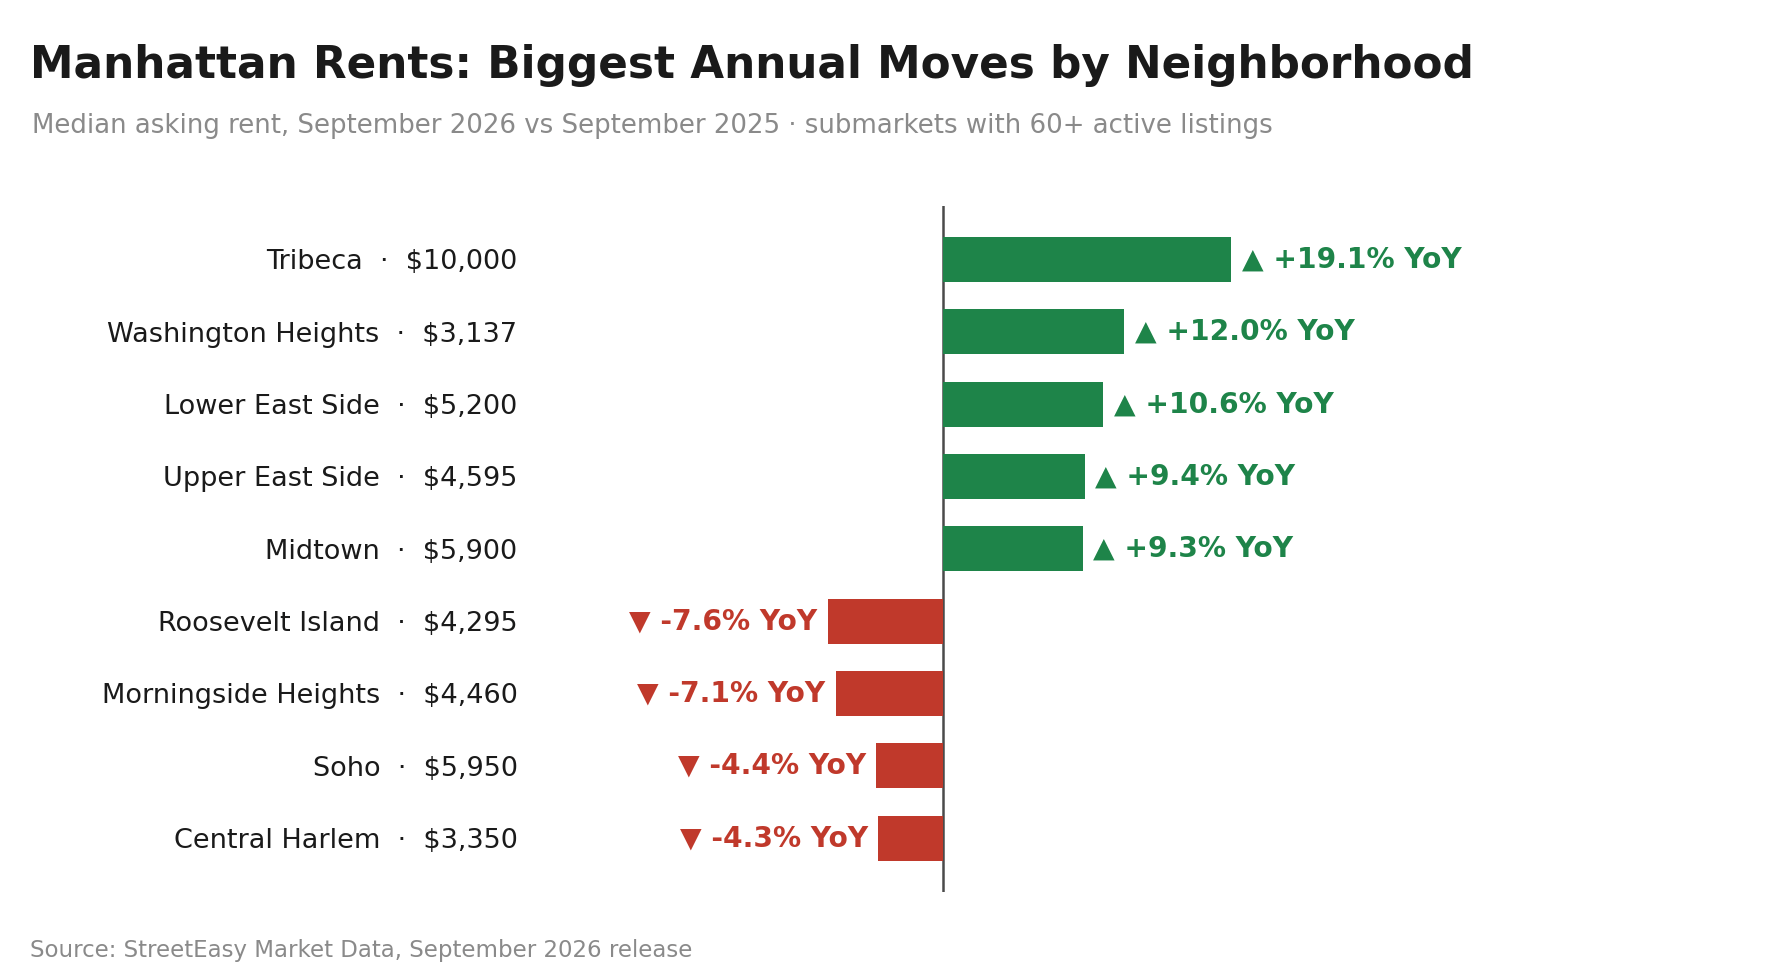
Central Park South ($14,250) and Tribeca ($10,000, up 19%) top the list. Washington Heights (+12%) and the Lower East Side (+11%) post the biggest gains among larger submarkets; Roosevelt Island and Morningside Heights are down about 7%.
For Renters: Renewing is often the better deal. If you move, look where rents are softening: Morningside Heights, Roosevelt Island and Central Harlem.
For Landlords: Inventory is the tightest in years, but one in five listings still cuts. Price at market on day one.
Source: StreetEasy Market Data, September 2026 release · median asking rent, active rental inventory, discount share · full market, uncapped · 27 Manhattan submarkets shown.
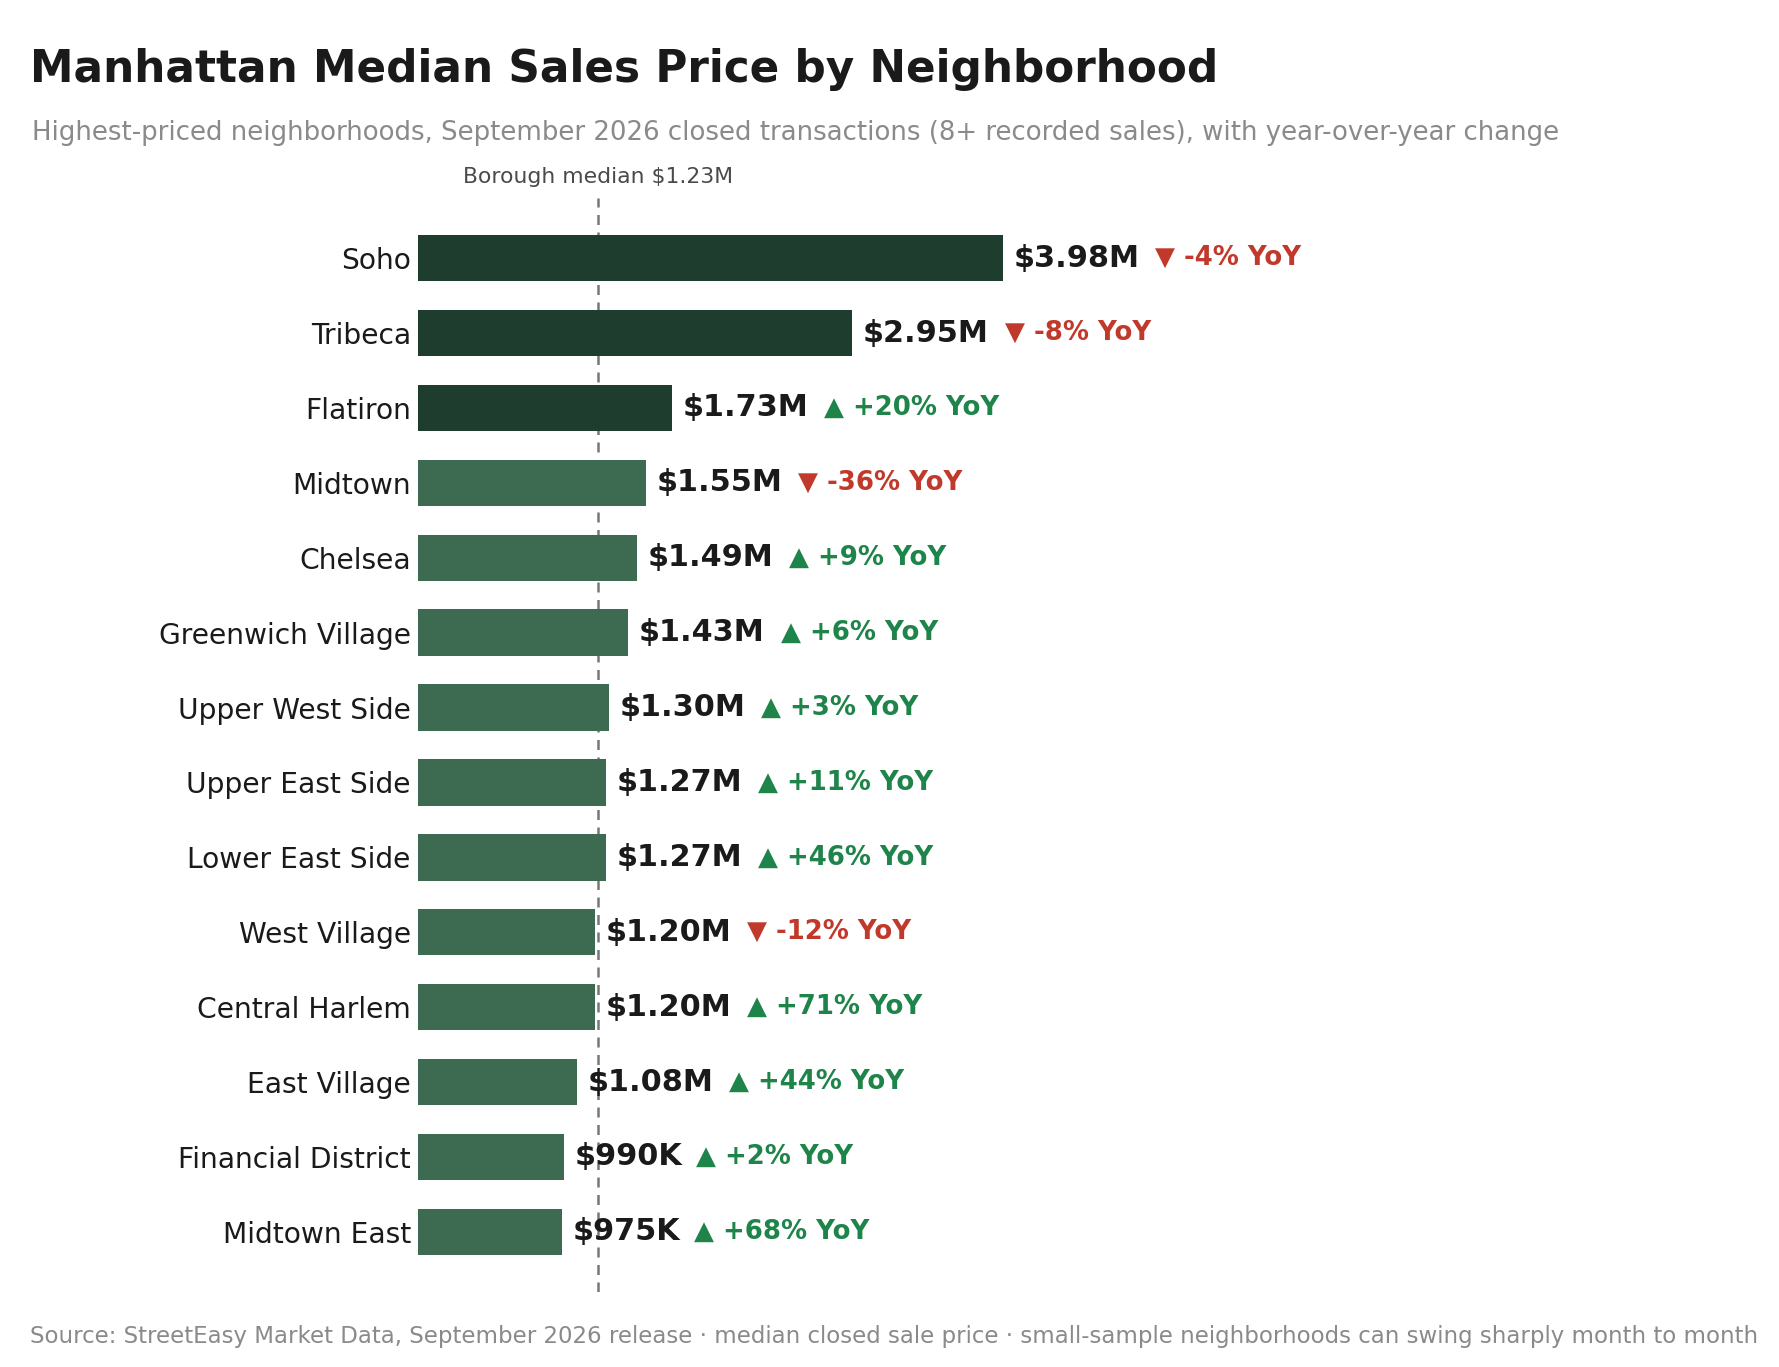
StreetEasy's September closings put the borough median at $1.23M. Among neighborhoods with eight or more recorded sales, Soho ($3.98M), Tribeca ($2.95M) and Flatiron ($1.73M) lead; Washington Heights ($490K) anchors the value end.
Mortgage Remarks
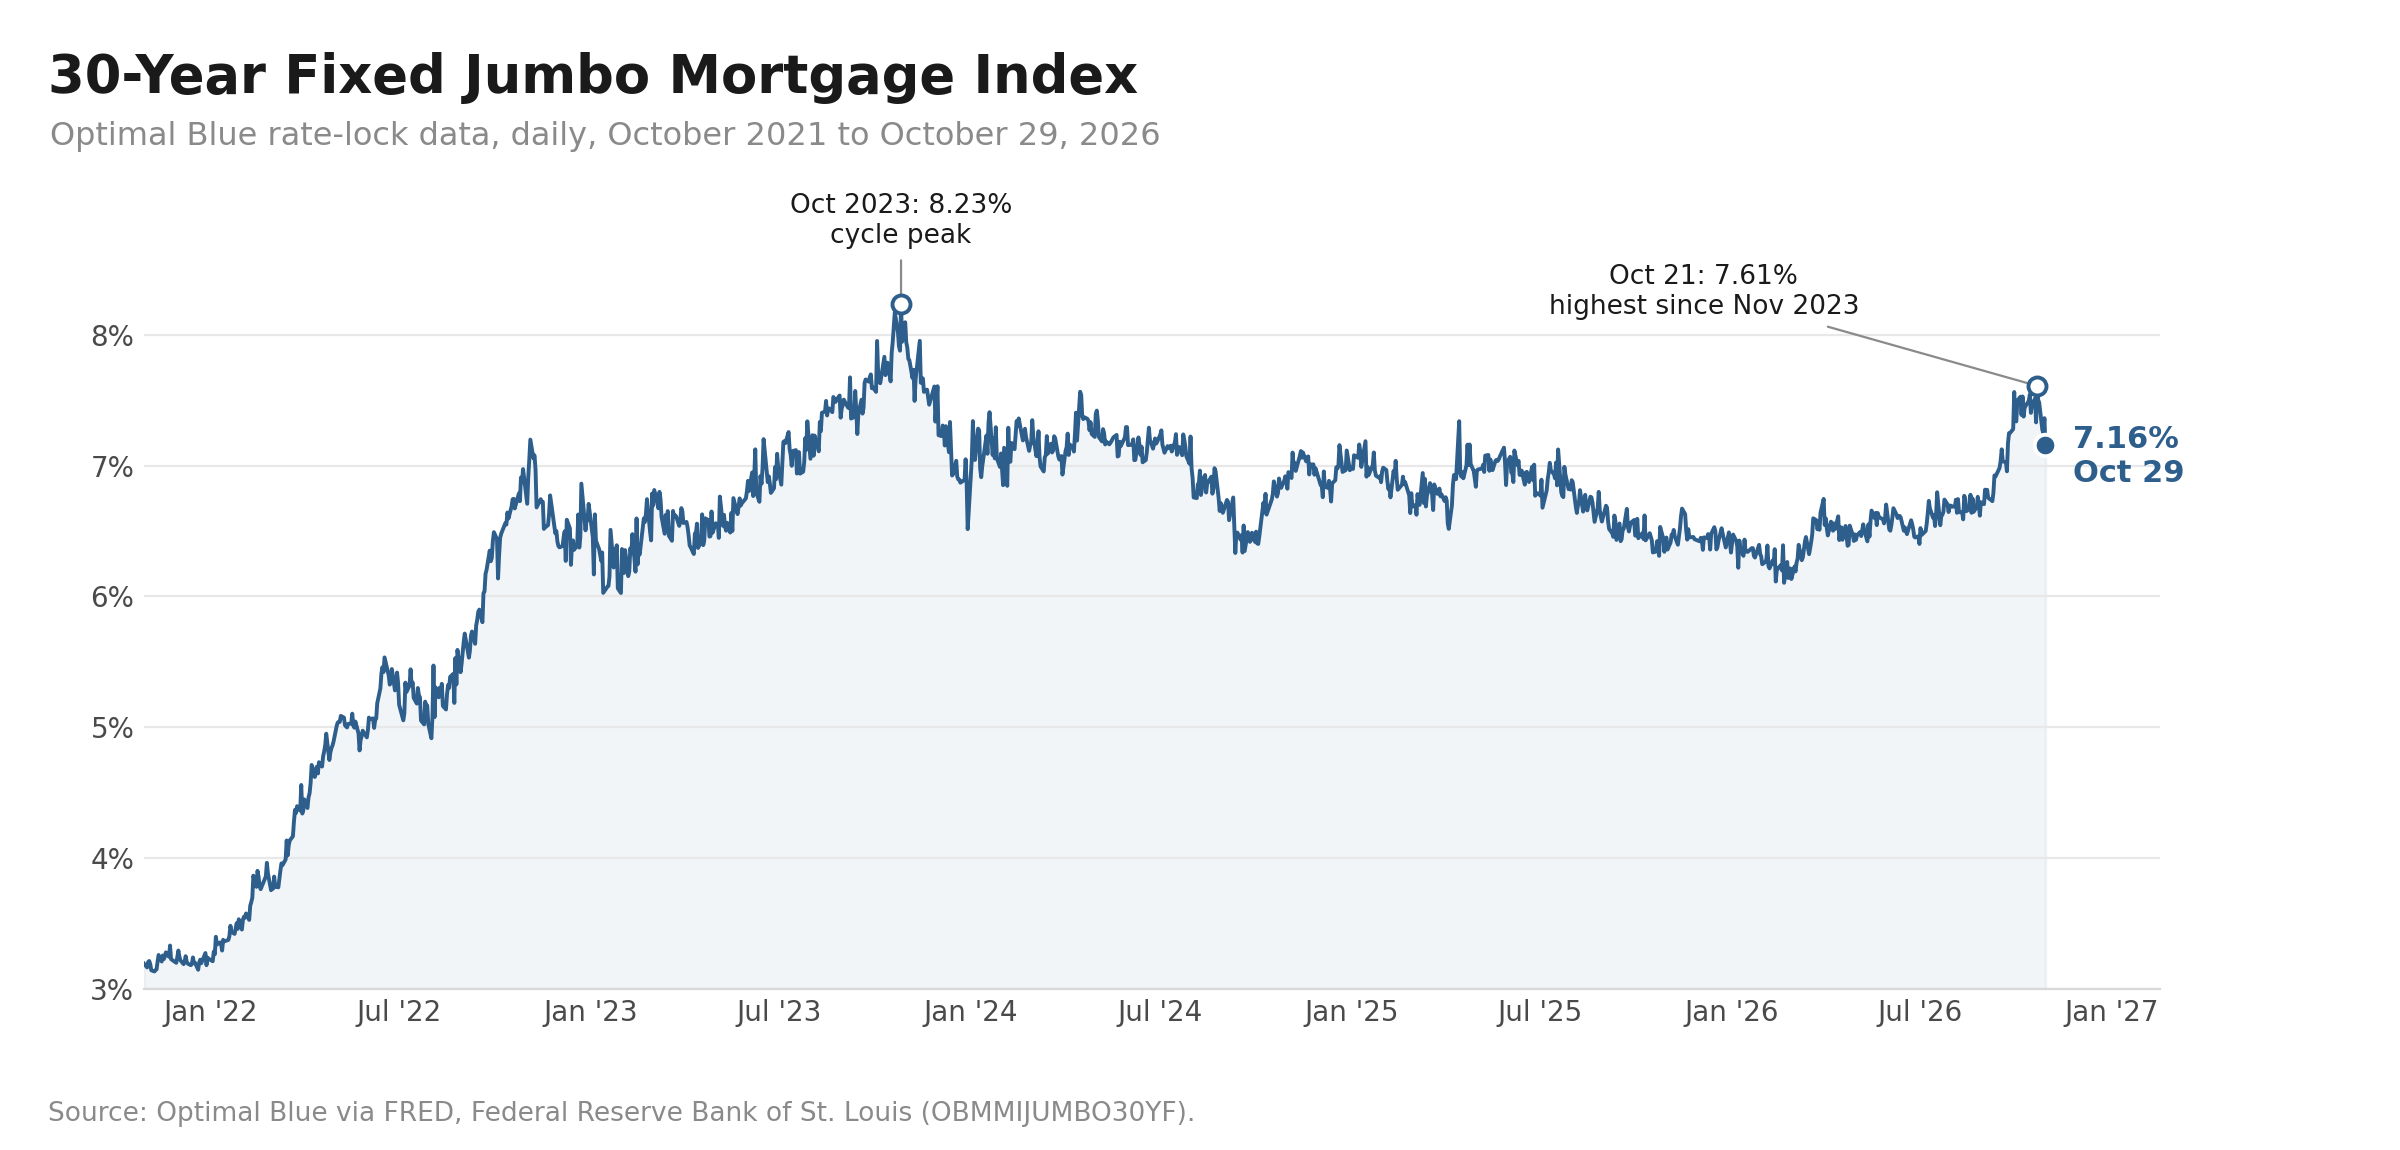
Courtesy of the Federal Reserve Bank of St. Louis (FRED): Optimal Blue 30-Year Fixed Rate Jumbo Mortgage Index, daily through October 29, 2026. It peaked at 7.61% on October 21, the highest since November 2023, then eased to 7.16%.
THE FED HOLDS, RATES EASE FROM THE PEAK
The Fed held rates at 3.75%–4% on October 28, after September's hike, with two members voting for another increase. Markets now price a hike at the December 8–9 meeting. The bond market did the easing: the 10-year Treasury peaked at 5.31% on October 5, then slipped back below 5% after an AI-led stock selloff sent investors into bonds, closing October at 4.94%. Freddie Mac's 30-year average eased to 7.24%, and our jumbo APR tracker read 7.29% on November 1, down from 7.44% a month earlier.
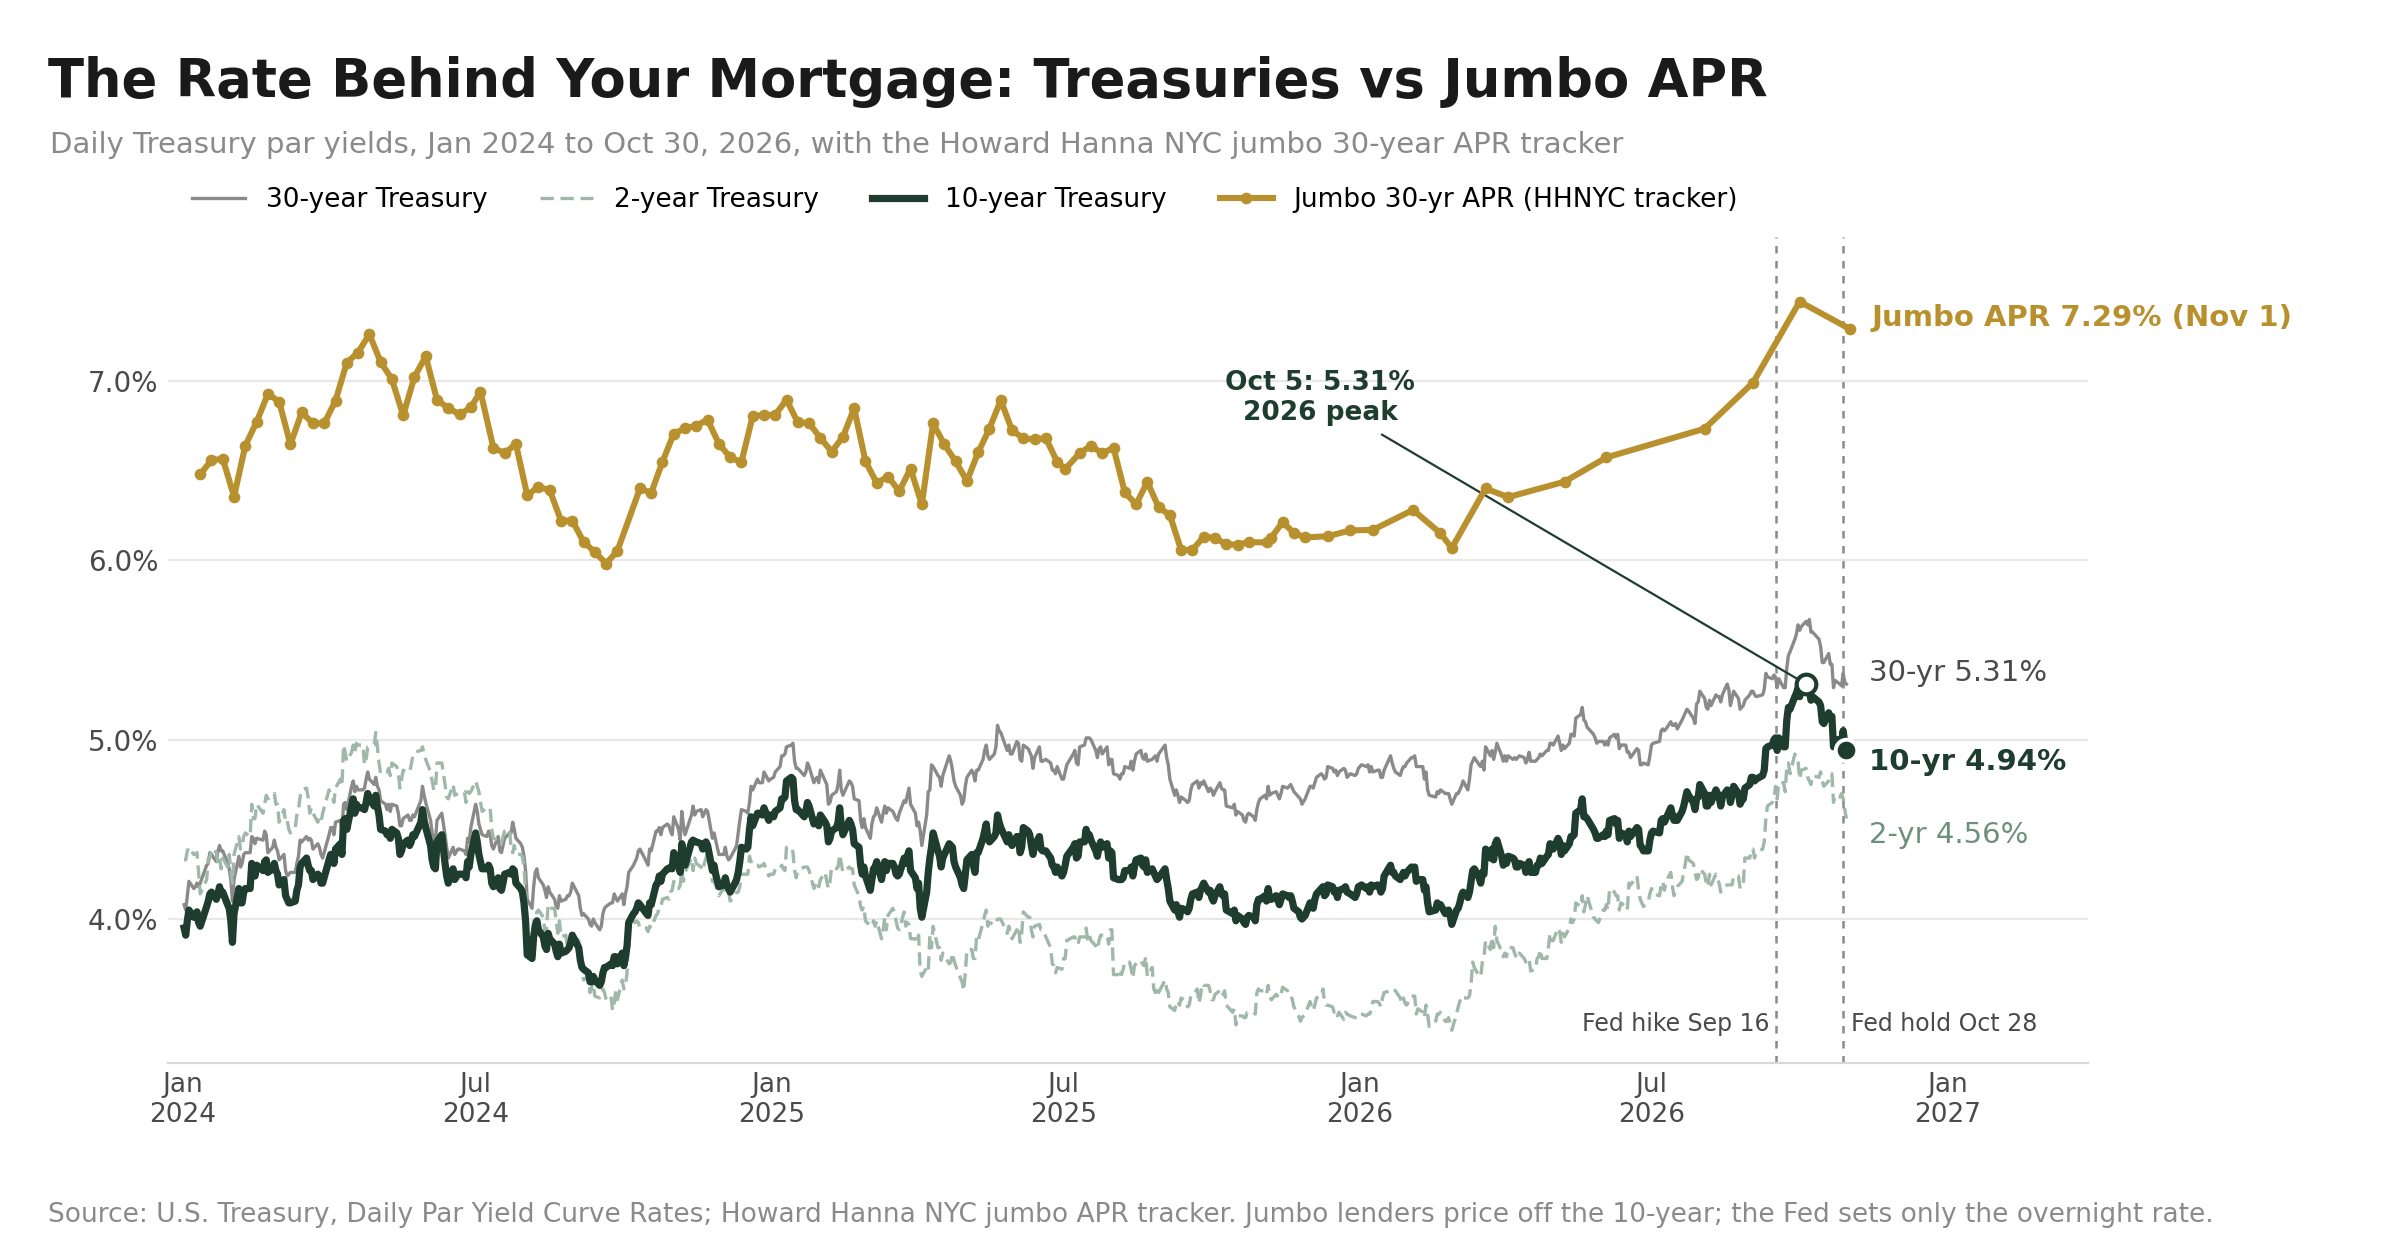
Source: U.S. Department of the Treasury, Daily Treasury Par Yield Curve Rates, January 2024 to October 30, 2026; Howard Hanna NYC jumbo APR tracker.
Buyers: Rates are down about 0.15 points from a month ago, roughly $100 a month less on a $1M loan. Lock once you are in contract; December's Fed meeting is a risk.
Sellers: Lower rates help at the margin. Rate-sensitive buyers below $1.5M are the first to return.
Consumer Sentiment
CONSUMER CONFIDENCE STUCK NEAR RECORD LOWS
The University of Michigan sentiment index was 48.0 in October, essentially unchanged from September and 10% below a year ago. Buying conditions for big-ticket items fell 18% on higher interest rates, and year-ahead inflation expectations rose to 4.7%. Higher is better; the long-run average is about 85.
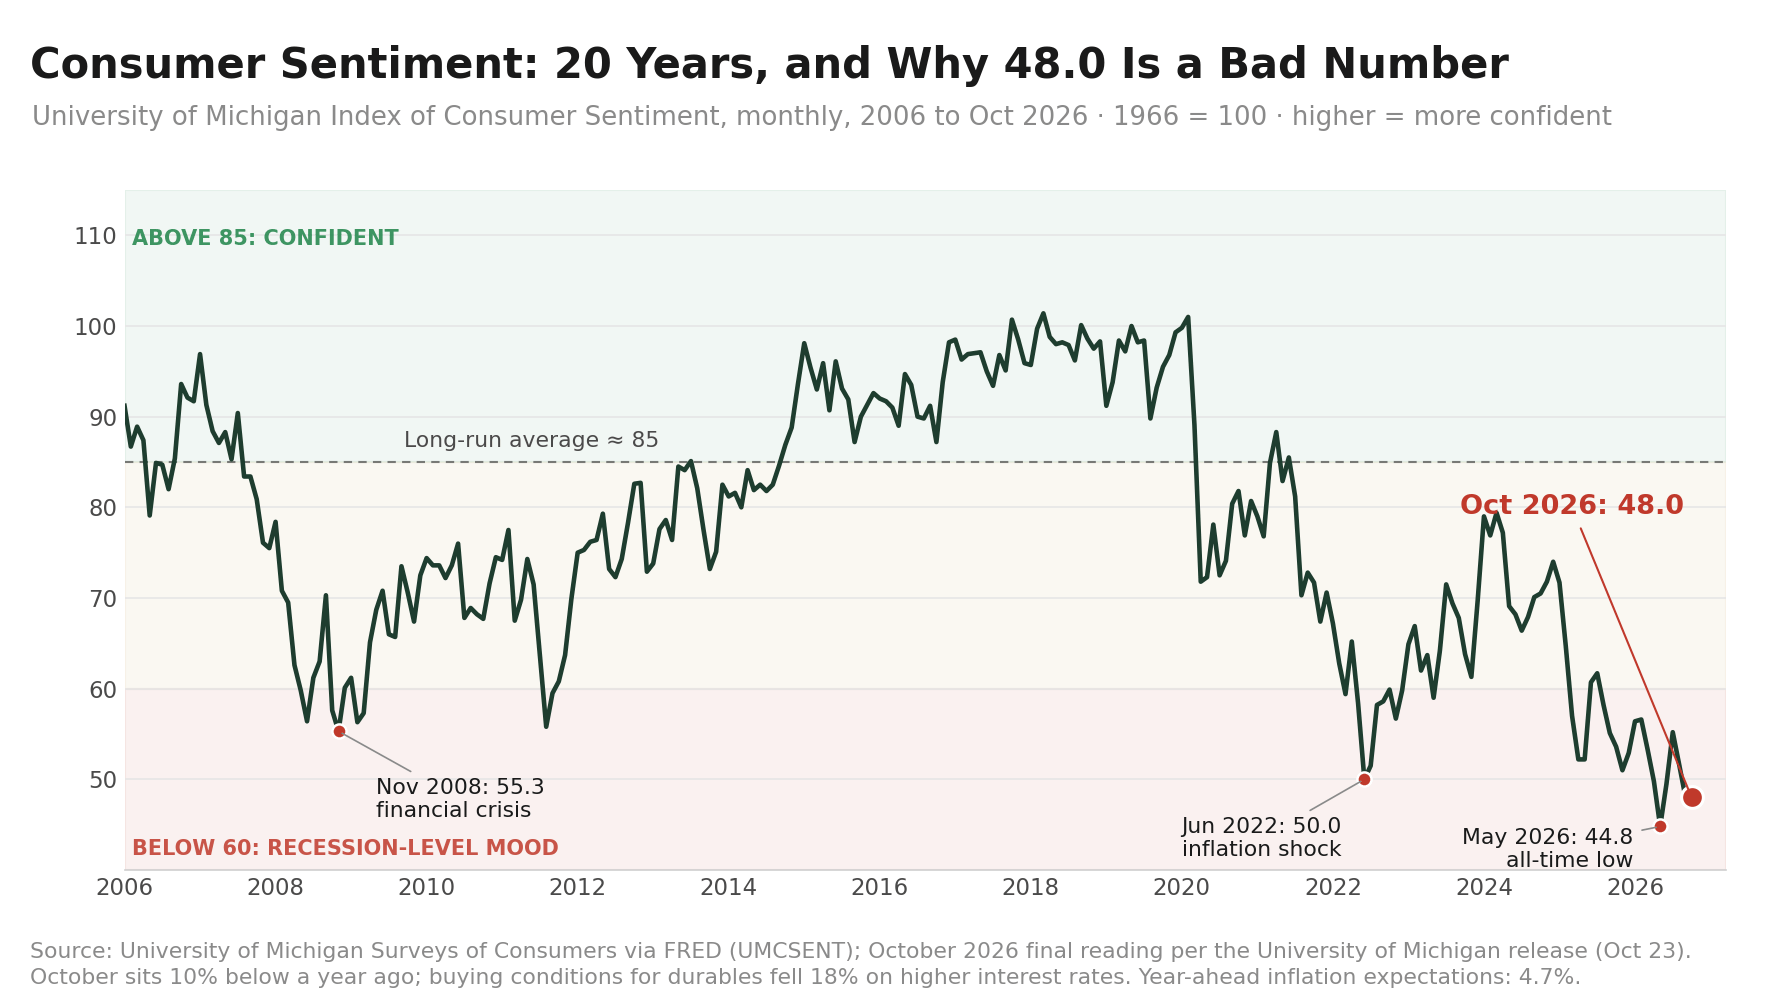
Manhattan buyers looked past the gloom: contracts jumped in October despite near-record-low confidence. Wealth, not sentiment, is driving the top of the market.
Buyers: Low-confidence months mean less competition. If your finances are ready, use it.
Sellers: Expect careful buyers. Answer hesitation with comparables and clean disclosure, not panic cuts.
Investor Insights
Domestic Investors and Yield
Rents up 8% a year against firm prices keep the income case intact. With the 10-year back below 5%, the bar has eased, but Manhattan's borough-wide gross yield of about 4.4% still trails it; income buyers should look uptown.
The Investor Yield Map
Inwood (9.0%), Washington Heights (7.2%) and Midtown East (6.7%) lead Manhattan on gross yield. Soho (1.8%) and Tribeca (2.6%) remain appreciation plays.
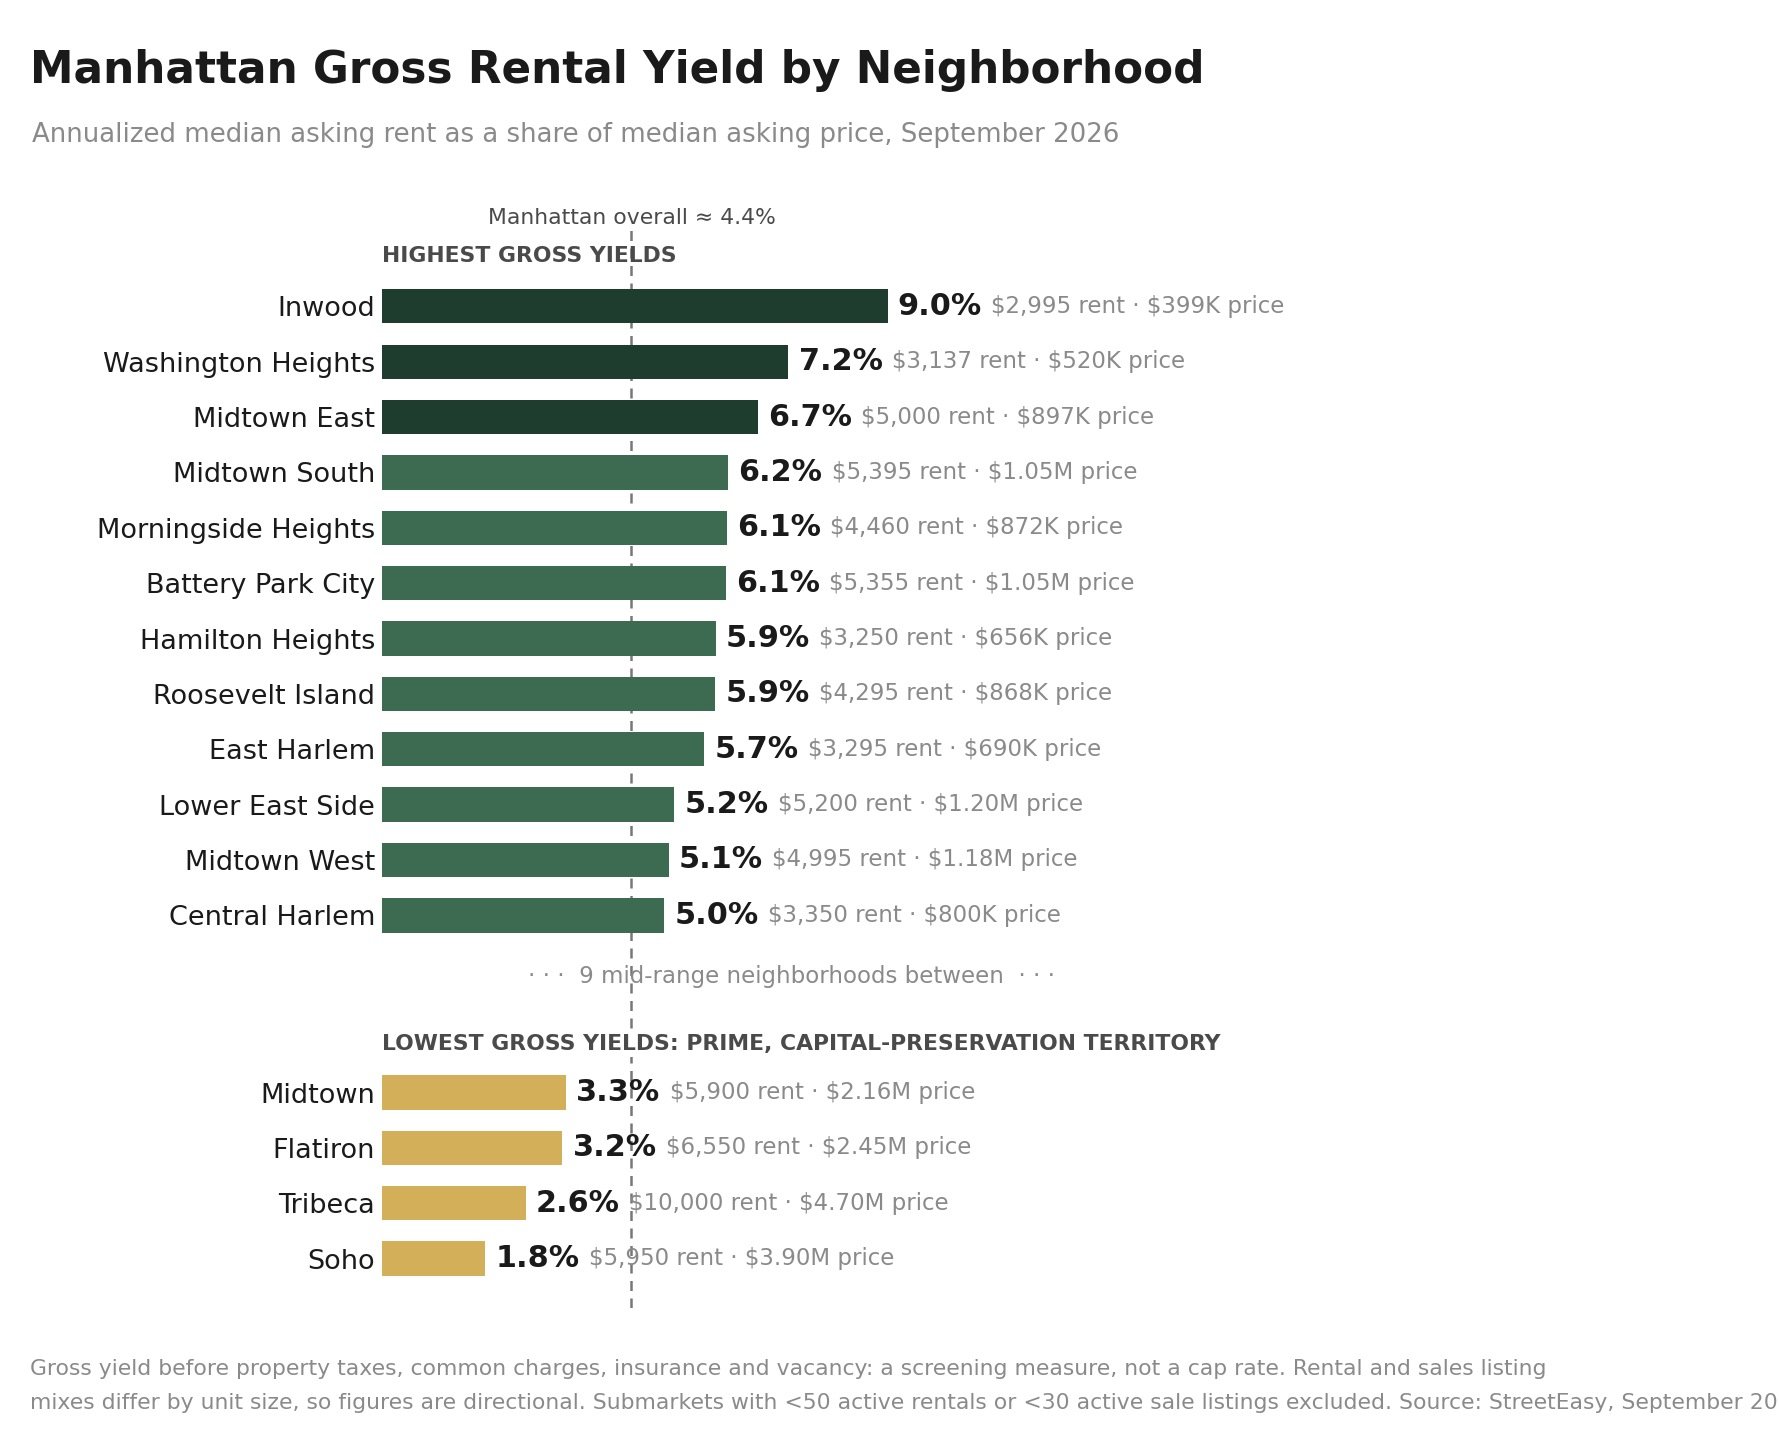
Method: gross yield = annualized StreetEasy median asking rent ÷ median asking price, both September 2026, same source and stage. A screening measure before property taxes, common charges, insurance and vacancy, not a cap rate. Submarkets with fewer than 50 active rentals or 30 active sale listings excluded.
Pied-à-Terre Surcharge: Bills Go Out as the Appeal Plays Out
The city is moving ahead with the surcharge while it appeals the September 29 ruling that ordered a redo of the rollout. The Appellate Division heard arguments on October 28 and appeared receptive to the city; a ruling is expected in early November. Separate lawsuits, including one from Wilbur Ross and Steve Wynn, challenge the tax itself as unconstitutional.
The exemption window closed October 13. Of roughly 17,000 owners first notified, about 11,000 applied and more than 6,800 have been exempted; fewer than 9,000 are now expected to pay. Bills are expected by mid-November, and the surcharge appears on the property tax bill due January 1, 2027.
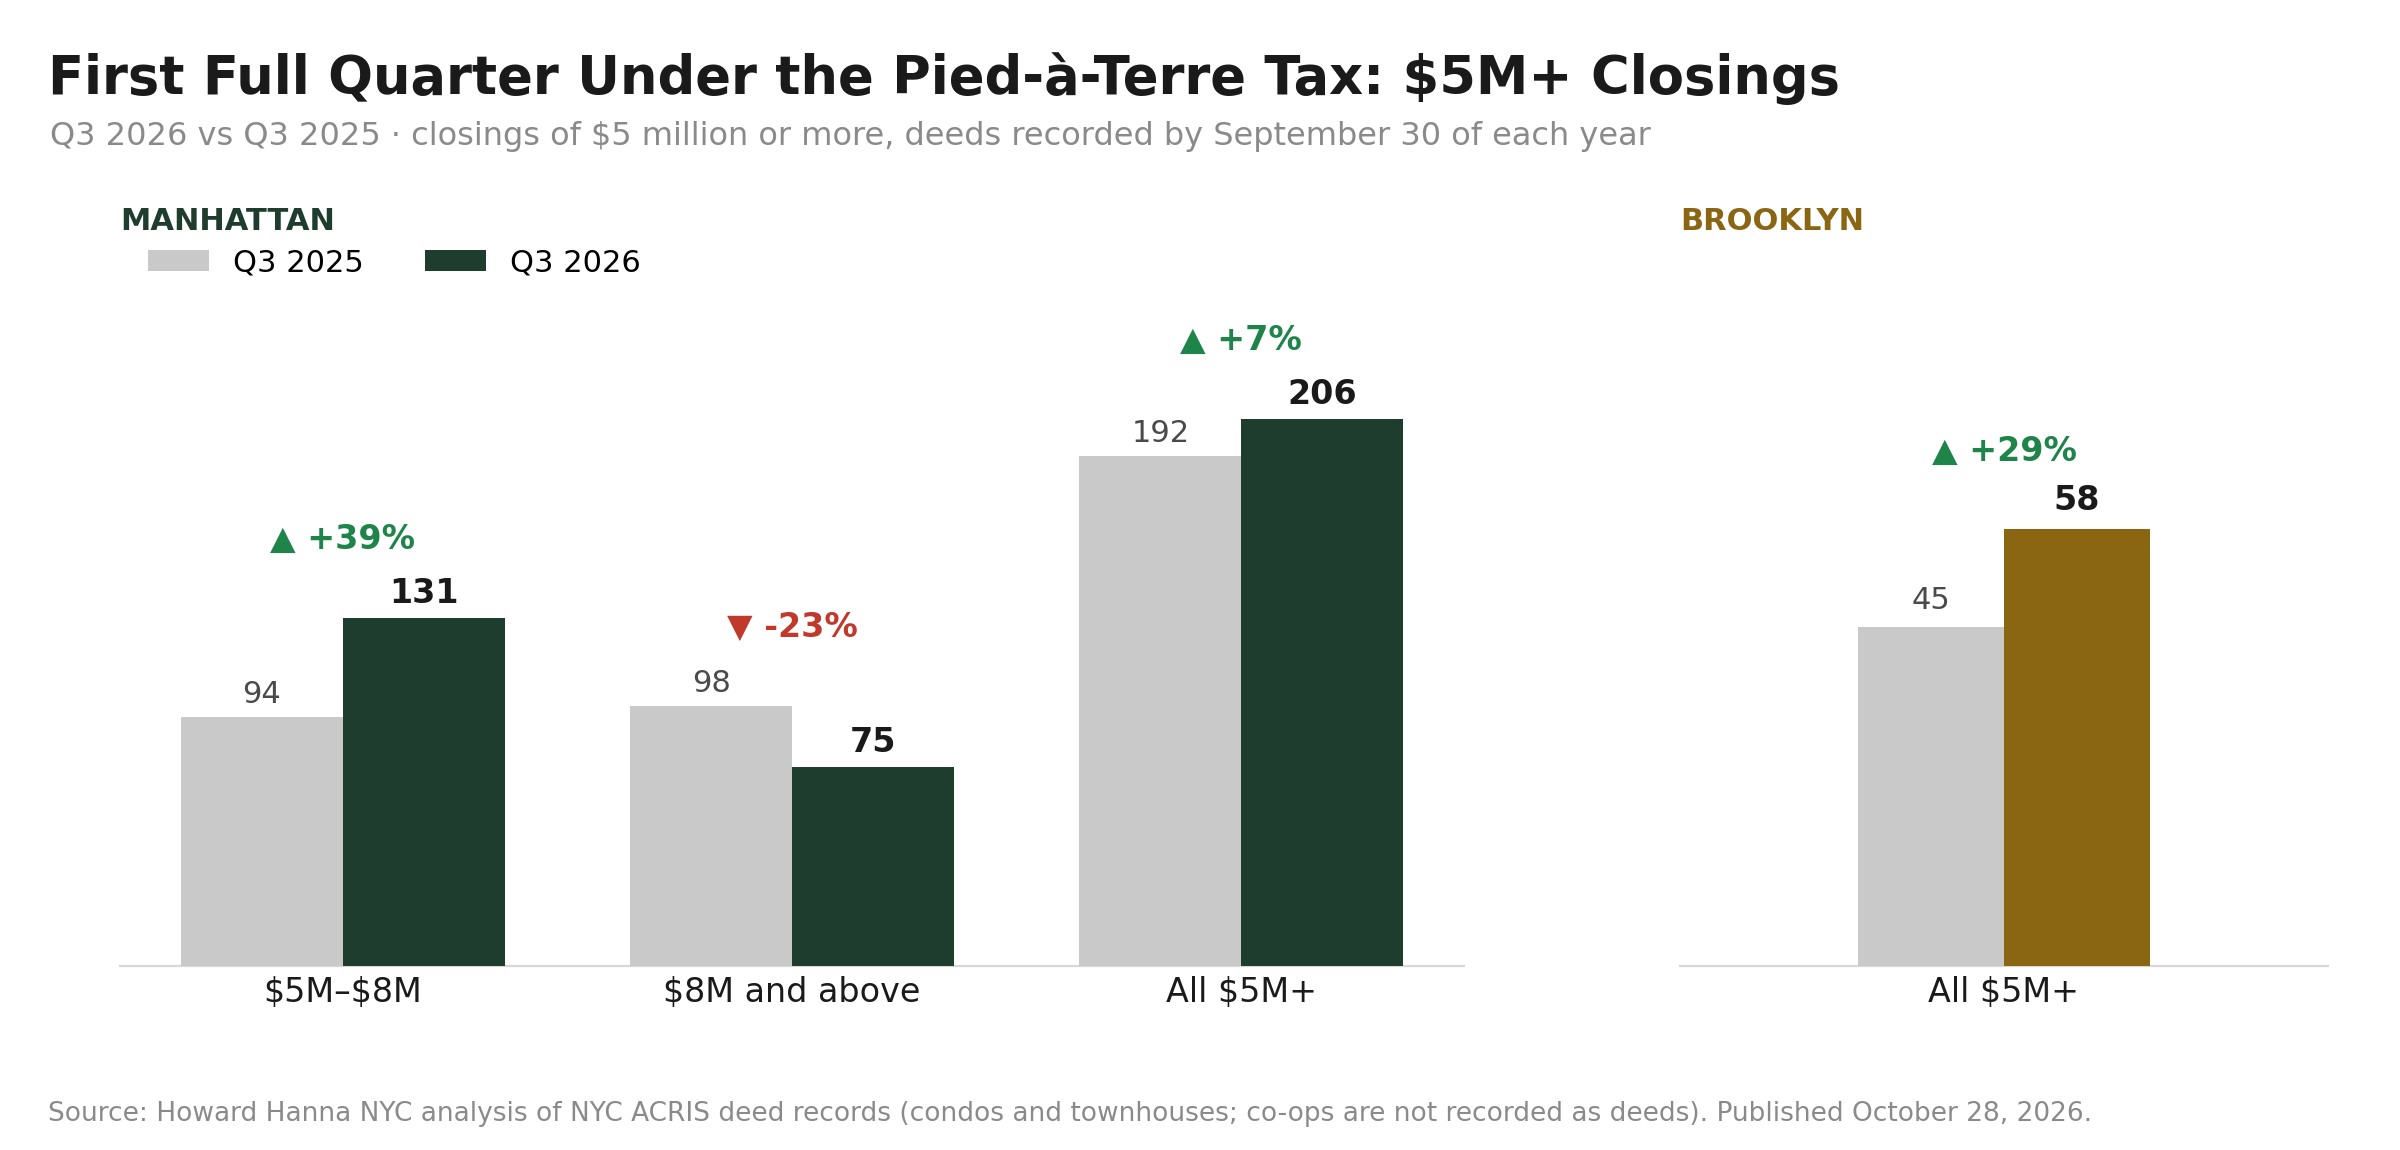
Our take: so far the surcharge is changing the mix, not the volume. Our ACRIS deed study found Manhattan's $5M+ closings up 7% in the first full quarter under the tax, but deals of $8M and above fell by about a quarter as buyers clustered in the $5M–$8M band. The sharper risk is administrative: full-time New Yorkers who hold title through an LLC or with partial ownership are being billed, as one Park Slope owner learned with a $47,504 notice. With a ruling due from the appeals court and Albany's tax debate set to resume after the November 3 election, the Governor having declined to pledge flat taxes, owners should review how title is held before the January bill. Full study: howardhannanyc.com/blog/nyc-pied-a-terre-tax-q3-2026-manhattan-luxury-sales
For Owners: If your exemption was denied or you dispute the city's value, the next step is the NYC Tax Commission. Do not assume the court case will cancel the bill.
For Buyers and Investors: Underwrite the surcharge on any non-primary condo or co-op the city values at $1 million or more. A unit with a full-time tenant is exempt; an empty pied-à-terre is not.
This is market information, not tax or legal advice. Howard Hanna NYC can tell you what your apartment would rent for and sell for today; your advisors should drive the exemption decision.
The Manhattan PPSF Story
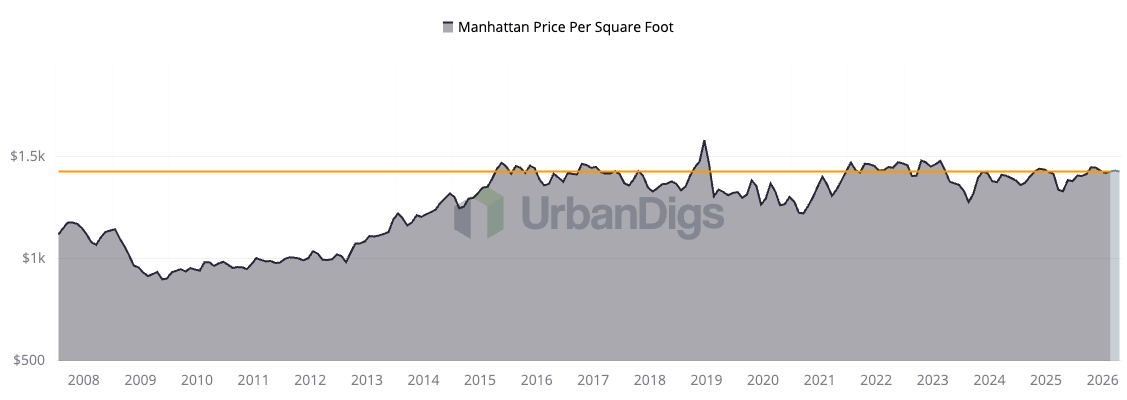
Manhattan's median PPSF has held a tight band for a decade. October's $1,428 sits near the top of it: scarcity, not speculation, is holding prices.
References
- Sales and pricing data (supply, demand, PPSF, listing discount, median sale price, days on market, price cuts, pending sales, Market Pulse) and Leverage Index inputs: UrbanDigs, October 2026 actuals.
- Bedroom-level median sale price: UrbanDigs Charts Room, 5-year monthly series, by closed date, October 2026.
- Rental data (asking rent, inventory, discount share, neighborhood table) and gross rental yield inputs: StreetEasy Market Data, September 2026 release.
- Sales by neighborhood: StreetEasy Market Data, September 2026 release (median closed sale price, recorded sales volume); StreetEasy September 2026 NYC Market Report, October 15, 2026.
- Closed-lease rental data: The Real Deal Rental Report by Jonathan Miller, September 2026. Rent-stabilized renewals: NYC Rent Guidelines Board Order #58.
- Mortgage rates: Howard Hanna NYC jumbo APR tracker (Bank of America, Chase, Wells Fargo), November 1, 2026; Freddie Mac Primary Mortgage Market Survey, October 29, 2026; Optimal Blue 30-Year Fixed Rate Jumbo Mortgage Index via FRED (OBMMIJUMBO30YF).
- Federal Reserve policy: FOMC statement, October 28, 2026. https://www.federalreserve.gov/newsevents/pressreleases/monetary20261028a.htm
- Treasury yields: U.S. Department of the Treasury, Daily Treasury Par Yield Curve Rates, through October 30, 2026.
- Gross rental yield: annualized StreetEasy median asking rent ÷ median asking price, by neighborhood, September 2026 release. Screening measure; thin submarkets excluded.
- Leverage Index: Howard Hanna NYC Leverage Index 2026; inputs courtesy of UrbanDigs. Demand, discount and PPSF charts: HHNYC Graphs workbook.
- Consumer sentiment: University of Michigan Surveys of Consumers, October 2026 final (released October 23); history via FRED (UMCSENT).
- Pied-à-terre surcharge: NYC Department of Finance, Non-primary residence surcharge, https://www.nyc.gov/site/finance/property/non-primary-residence-surcharge.page; The Real Deal, October 28 and October 29, 2026; New York Daily News, October 14, 2026; New York Post, October 28, 2026; New York State Supreme Court, Richmond County, decision of September 29, 2026; Howard Hanna NYC, The First Full Quarter Under NYC's Pied-à-Terre Tax (ACRIS deed analysis), October 28, 2026, https://howardhannanyc.com/blog/nyc-pied-a-terre-tax-q3-2026-manhattan-luxury-sales. Not tax or legal advice.
Questions About This Month’s Market?
If you’d like to discuss what this month’s data means for a specific property, portfolio, or search, feel free to reach out to the Howard Hanna NYC team.
Howard Hanna NYC brings the nation’s largest independent and family-owned brokerage to New York City, uniting the strength of a national network with the insight and sophistication of a local firm. Formed through joining forces with Elegran Real Estate, Howard Hanna NYC delivers a seamless, full-service experience backed by more than 15,000 agents across 500 offices in 14 states.